For a week in the middle of June 2026, the fastest way to raise nine figures was to put the word “sovereign” in your deck. Four companies did exactly that, and the capital arrived: Dream closed $260 million, Sarvam closed the first $234 million of a $300 million round, Odyssey raised $310 million, and General Intuition was reported in talks for roughly $300 million more. None of them mean the same thing by “sovereign.” All of them got paid for it.
The cluster is not a coincidence, and it is not pure narrative momentum. It traces back to a specific event eight days earlier — the June 12 export-control shutoff that ordered Anthropic to bar two frontier models from every foreign national on earth. One of the clearest descriptions of Dream’s raise made the causal chain explicit:
Dream Security ($260M, co-led by Group 11 + Bicycle Capital): Israeli sovereign AI and cyber defense company with $300M in orders since late 2024, ARR recently crossed $100M, valued at $3B. Round accelerated by US access restrictions on frontier models, driving governments to seek sovereign LLM alternatives.
— @fundable_ai Jun 19, 2026
That sentence — “round accelerated by US access restrictions” — is the thesis for the entire week. When the United States demonstrated it could unplug a shipped model by letter, every government and regulated enterprise that depended on someone else’s API learned the same lesson at once: access you don’t control is a liability you can’t price. The raises are the market putting a number on that lesson.
The four raises, mapped
| Company | Raised | Valuation | What “sovereign” means here | Backers |
|---|---|---|---|---|
| Dream | $260M | $3B | Nation-owned AI + cyber defense for governments | Bicycle Capital, Group 11, Antler, Bain Capital Ventures |
| Sarvam | $234M (first close of $300M) | $1.5B | India’s full-stack national AI stack | HCLTech ($150M), Bessemer, Khosla, Peak XV |
| Odyssey | $310M (Series B) | $1.45B | World models of physical reality | Natural Capital (lead), Amazon, AMD Ventures, GV, EQT, IQT |
| General Intuition | ~$300M (in talks) | ~$2B | World models trained on game footage | Reported: Jeff Bezos, Eric Schmidt |
Read the third column carefully, because it splits the table in half. Dream and Sarvam are selling jurisdictional control — the promise that a government or a nation can own and run frontier capability without depending on a foreign vendor’s terms of service. Odyssey and General Intuition are doing something entirely different: building world models, a separate frontier from large language models, that learn physics and causality rather than text. They landed in the same week’s “sovereign AI” coverage mostly because the phrase was hot.
That conflation is the most useful thing to notice. “Sovereign AI” is currently doing the work of at least two unrelated theses, and the capital is flowing to both under one headline.
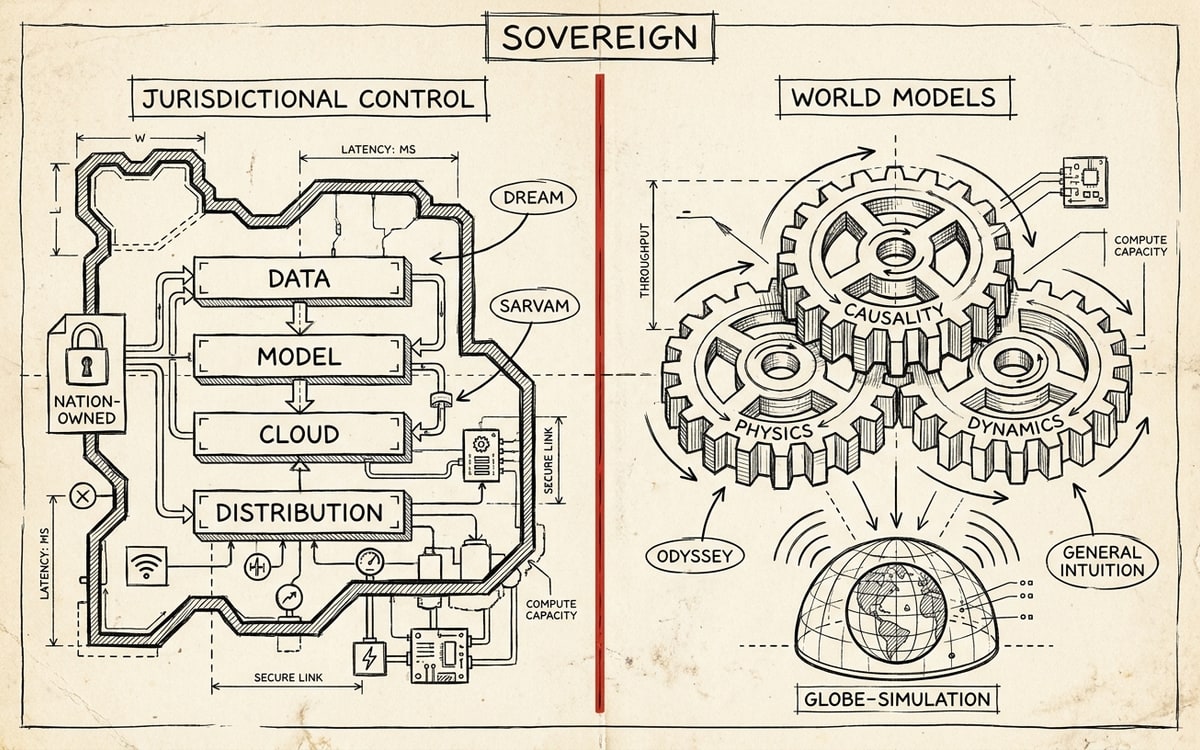
Bet one: sovereignty as jurisdictional control
Sarvam is the cleanest example of the first thesis, and its framing is explicitly national. The company called itself “India’s full-stack sovereign AI company,” and its cofounders cast HCLTech’s $150 million lead check not as a normal venture round but as proof of national capacity:
HCLTech’s investment in Sarvam shows India now has the capital structure to build sovereign AI.
— Pratyush Kumar and Vivek Raghavan, cofounders of Sarvam AI, Moneycontrol, Jun 15, 2026
The detail that matters is who wrote the largest check. Not a Silicon Valley fund — HCLTech, an Indian IT-services giant, taking a 10.46% strategic stake. That is the structural signal: sovereign AI gets funded by domestic strategic capital, because the entire pitch is independence from foreign capital and foreign infrastructure. A US fund leading Sarvam’s round would have undercut the thesis it was buying.
Dream sits at the harder end of the same bet. Its customers are governments and critical infrastructure operators, its founding team includes a former Austrian chancellor and the former CEO of NSO Group, and its $300 million in orders since late 2024 means the demand was already there before the export shutoff lit the fuse. The shutoff didn’t create Dream’s market. It compressed the timeline — turning a slow government-procurement cycle into an urgent one.
Bet two: world models, wearing the same word
Odyssey and General Intuition are not sovereignty plays at all, and pretending otherwise misreads what they’re building. Odyssey raised $310 million at a $1.45 billion valuation to build world models — AI that simulates physical reality, causality, and dynamics rather than generating text. One concise summary of the round:
A world-model startup just raised a $310M Series B at a $1.45B valuation — led by Natural Capital, with Amazon, AMD Ventures, GV, EQT and In-Q-Tel in the round — and almost none of the frontier-AI attention this week pointed at it. That gap is the opportunity.
— @stretchcloud Jun 22, 2026
The In-Q-Tel participation (the CIA’s venture arm) is why this gets swept into “sovereign” coverage, but that’s strategic-investor signaling, not a sovereignty product. Odyssey and General Intuition (the latter spun out of gaming-clip platform Medal, training agents on billions of game frames) are betting that the next frontier is models that understand space and time, a category orthogonal to the LLM export fights entirely. They benefit from the same flood of capital chasing “the next thing after LLMs,” and the sovereign-AI headline is a convenient umbrella, not an accurate one.
Why the label won’t survive
The honest reading of this week is that “sovereign AI” is a phase, not a category. It is what the market calls a cluster of bets before it learns to tell them apart. The same thing happened to “Web3” and “metaverse” — a single word stretched across incompatible theses until buyers forced precision.
Procurement will force it here. A government buying Sarvam or Dream is buying jurisdictional control: where the weights live, who can switch them off, whose law governs the data. A studio licensing Odyssey is buying a physics simulator. These are different products sold to different buyers solving different problems, and the moment a procurement officer writes a requirements doc, the word “sovereign” splits into the things it was actually standing in for — data residency, model ownership, kill-switch immunity, compute independence.
One observer put the deeper version of this critique well during the same stretch:
The discussions around sovereign AI often focus on whether a country has its own model, but that is incomplete. A country can have its own model and still remain dependent on external systems for data access, distribution channels, cloud dependencies, and integration layers where intelligence is actually used.
— @_PradeepGoel Jun 22, 2026
That is the question the funding wave hasn’t answered yet. Owning a model is the easy, fundable, headline-friendly part of sovereignty. The hard part, owning the data pipelines, the cloud, the distribution, the integration layers where the model actually does work, is where dependence quietly persists. Dream and Sarvam raised on the promise of the whole stack. Whether the capital buys the whole stack, or just the model on top of someone else’s infrastructure, is what the next year decides.
For now, the week’s lesson is narrower and certain: the export shutoff gave sovereignty a price. Roughly $1.1 billion flowed to companies selling some version of “you’ll never have to depend on a model someone else can turn off.” The buyers believe it. The map above is where they placed their bets — and half of them are betting on a word that means two different things.