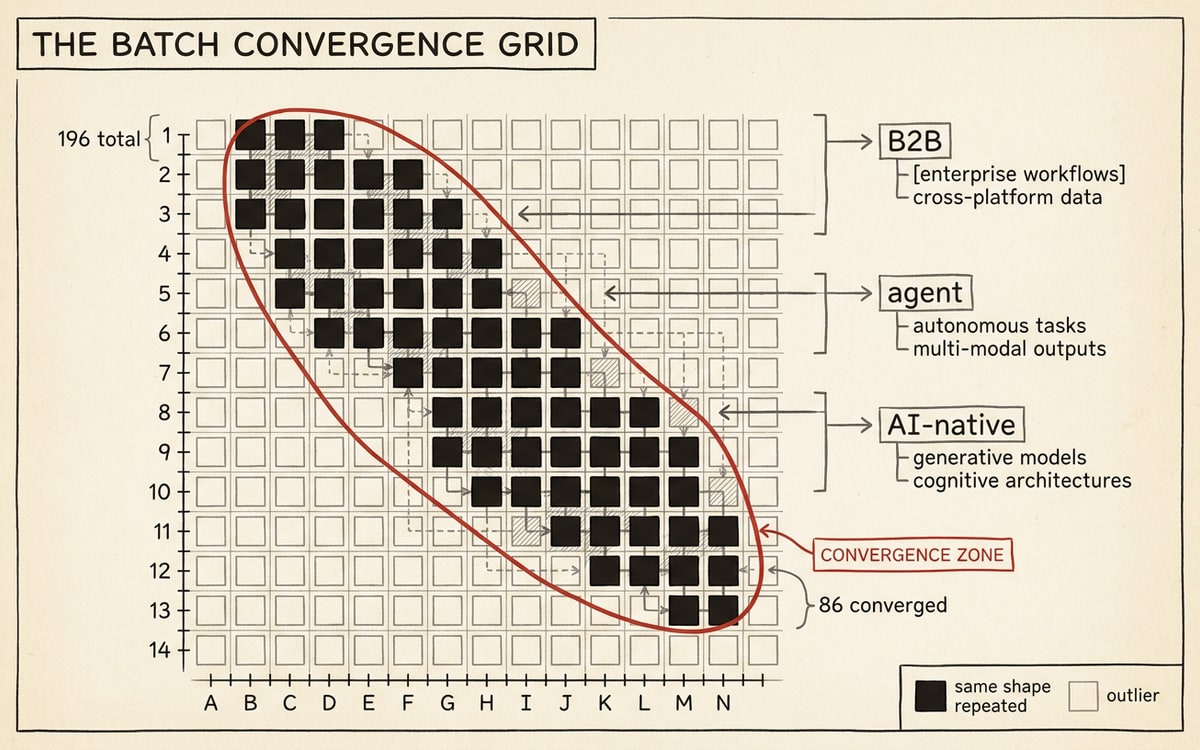
A founder named Chris Lu, who built and sold the AI writing company Copy.ai, spent a chunk of June reading the pitch of every company in Y Combinator’s Spring 2026 batch — all 196 of them, all 395 founders — and published the tally. The headline number wrote itself: 95% of the batch touches AI, and only ten companies use none at all. But the number that matters is quieter and stranger. By his count, eighty-six companies, forty-four percent of the entire batch, are the same company. Not similar. The same shape: an AI-native business that sells software to other businesses where the agent is the product, not a feature inside it.
When nearly half a cohort converges on one idea, the interesting question is no longer whether the idea works. It is what the convergence is a bet on.
The map checks out
Before trusting any single founder’s spreadsheet, the claims are worth checking against the primary record. YC publishes its batch directory in machine-readable form, and the Spring 2026 file lists exactly 196 active companies. The structural splits hold up cleanly against it: 120 of those 196 are tagged B2B (61%, against Lu’s 62%), and the consumer column has precisely 12 entries — the same number he reports. The named companies he singles out are all real and all in the file: Tenet Industries (“low-cost, mass-producible strike drones”), 9 Mothers (“counter-drone systems… we delivered for the DoW”), Apollo Atomics (“the most compact nuclear reactors”), and a tight cluster of prediction-market infrastructure plays led by Oddpool (“institutional infrastructure for prediction markets”).
The structural shape of the batch, in the numbers that survive cross-checking against the public directory:
| Dimension | Count | Share | Cross-check |
|---|---|---|---|
| Total active companies | 196 | 100% | YC OSS directory ✓ |
| B2B | 120 | 61% | Lu: 62% |
| Consumer | 12 | 6% | Lu: 12 (exact) |
| Build LLM agents | 137 | 70% | directory scan ~50%, pitches 70% |
| AI-native B2B Agent-as-a-Service (one shape) | 86 | 44% | Lu’s central claim |
| Touch AI at all | 186 | 95% | only 10 use none |
| Defense / drone / aerospace | ~13 | 7% | hardware hedge |
| Industrials column | 23 | 12% | directory tag |
One claim is worth tightening rather than repeating. The “six prediction-market companies” figure stretches to fit: two of the six (a startup building US stock perpetuals for Indian traders, and “the IDE for investors”) are fintech adjacent, not prediction-market rails. The pure-play cluster building the plumbing for Polymarket and Kalshi is closer to four. It is a small overcount, but it points at the one thing a batch analysis built from pitch copy cannot fully resolve: the difference between what a company says it is and what it is.
The agent number survives that same scrutiny in the other direction. The public directory’s one-line descriptions are terse — a text scan of them surfaces agent language in about half the batch. Lu, reading full pitches, puts it at 137 of 196, or 70%. Both can be true: the directory undersells, the pitches oversell, and the real figure sits between. What is not ambiguous is the trajectory. Run the same crude scan across the three prior batches and agent-mentions climb from the high thirties and low forties of a percent into the fifties for Spring 2026. The agent share is not flat. It is the steepest-rising line in the dataset, and it is the empirical version of the prediction we made three weeks into the batch from the early company list.
The 10x thesis, executed
The convergence is not an accident of the batch. It is the batch doing exactly what it was told.
In late 2024, on its own Lightcone podcast, Y Combinator made the call explicit in a title that has since become a slogan: “Vertical AI Agents Could Be 10X Bigger Than SaaS.” Garry Tan put the arithmetic on the table himself.
SaaS has grown 10x per decade for a few decades now. This is the next 10x: vertical AI agents.
— Garry Tan, LinkedIn, Nov 2024
Spring 2026 is the first batch selected, funded, and assembled entirely under that doctrine. The eighty-six-company cluster is not a coincidence of founder taste — it is a thesis propagating through an accelerator’s filter. YC told the world’s most ambitious technical founders that the largest software opportunity of the decade was a vertical agent that does a job rather than a tool that assists one, and the application pool answered with eighty-six versions of the same answer. The key word in the slogan is the one founders internalized most literally.
Y Combinator’s bet: “Vertical AI agents could be 10x bigger than SaaS.” The key word is vertical — agents that do the whole job, not tools that assist.
— @lkstimm Jun 14, 2026
You can see the same shape from the other side of the cap table. a16z’s Olivia Moore spent a week meeting the batch and posted her own field notes, and they read like an independent confirmation of Lu’s tally — arrived at by talking to founders rather than counting them.
The broker and the agency are becoming software. Founders are taking businesses that have always run on human middlemen and rebuilding them as agent-run platforms.
Vertical AI is (often) routing around incumbents, not integrating with them. For many founders, the new playbook is to skip the official API entirely so legacy software can’t shut you off.
— @X Jun 14, 2026
This is the same machine The Deep Feed traced two weeks ago, when a16z published a manifesto calling small businesses the next frontier for AI and wired three term sheets to match it in a single week. It is the same machine Sequoia named “services-as-software” — stop selling the tool, sell the work. The S26 batch is what that thesis looks like when it stops being an essay and becomes a cohort.
When the moat is the thing everyone copied
Here is where the celebration and the warning sit in the same number.
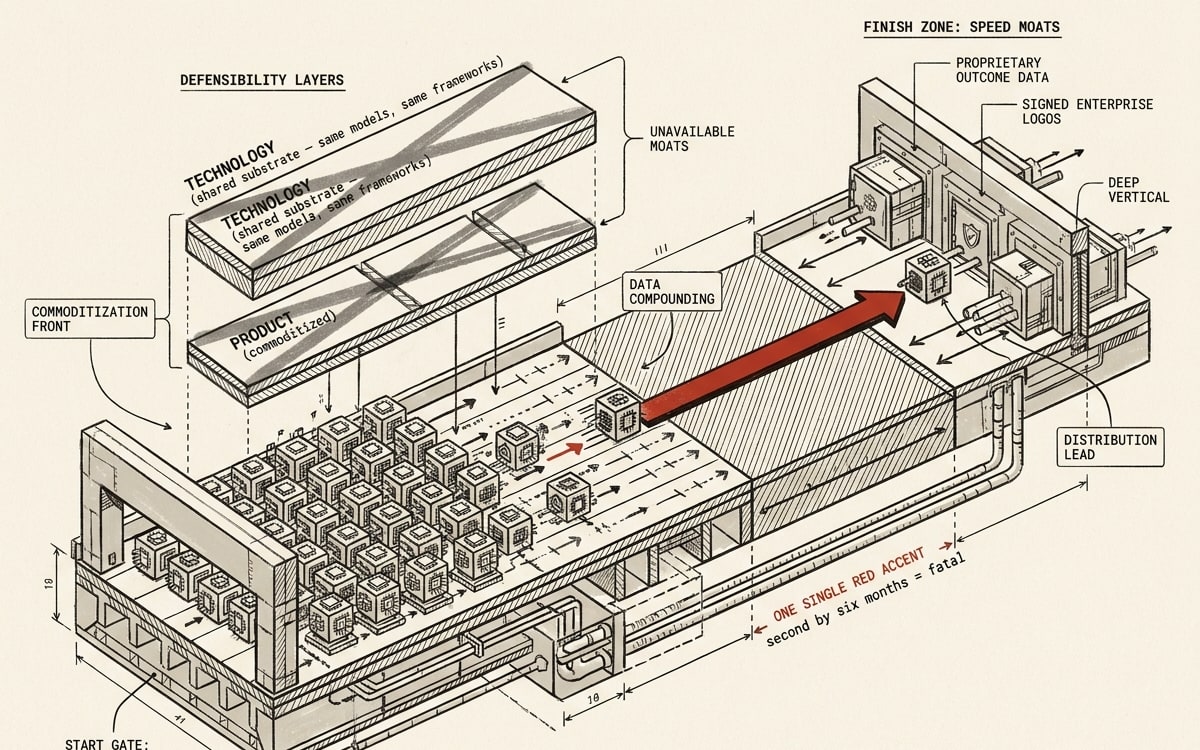
A vertical agent that replaces labor instead of assisting it is a genuinely larger prize than the SaaS seat it displaces — that part of the 10x thesis is sound, and the batch is right to chase it. But a thesis this legible produces a predictable failure mode: everybody can read it. The 86-company cluster is not 86 secrets. It is 86 teams who all read the same Lightcone episode, all saw the same Sequoia essay, and all pointed an agent at a back-office job in a fragmented industry. The technology is not the differentiator, because the technology is a shared substrate: the same handful of frontier models, the same agent frameworks, the same computer-use tricks for routing around legacy APIs that Moore describes.
When the product is commoditized, the moat has to come from somewhere else: the specific vertical, the proprietary outcome data, the speed of getting to the customer before the other fifteen teams aiming at the same desk. Lu’s own conclusion names this precisely.
AI is no longer the differentiator. For most of these companies the value is clear and the product is faster to build, so execution is the core advantage. This batch won’t be won on insight. It’ll be won on speed.
He means it as optimism, and for the winners it will be. But read structurally, “won on speed” is not a feature of the batch. It is a confession about it. Speed is the moat you reach for when you do not have another one. A market won on execution velocity is a market where the underlying product cannot defend itself — where being second by six months is fatal not because the leader’s technology is better but because the leader signed the logos first and now owns the outcome data that makes the next version better. The batch has made, at institutional scale, a wager that distribution and data compounding will outrun commoditization. That is a real strategy. It is also the opposite of a durable advantage.
The companies that quietly hedged
The most interesting companies in the batch may be the ones that did not take the bet.
In a cohort where 95% touch AI, several of the most differentiated entries barely use it, and many build physical things. There are roughly thirteen defense, drone, and aerospace companies — mass-producible strike drones, a counter-drone OS already selling to the Department of War, satellites for in-space manufacturing, and a compact nuclear reactor from an MIT-trained nuclear engineer. The directory’s “Industrials” column alone holds 23 companies. These are not AI-native B2B AaaS plays, and that is precisely their advantage: a strike drone’s moat is manufacturing capacity and a defense contract, neither of which the next clever prompt can erode. The hardest thing to copy in an agent batch turns out to be the company that isn’t an agent.
Then the small, specific clusters that signal where founders think the next platform fights are: the four-or-so teams building the financial plumbing for prediction markets, betting that Polymarket and Kalshi become a new asset class that needs a prime brokerage; the handful building the AI-security layer for the agents everyone else is shipping, selling shovels in the agent gold field; the deep-tech and bio hardware plays with Caltech and Oxford PhDs that have no software comp at all. None of these is the median company. All of them are betting on a moat that survives commoditization — capital intensity, regulatory surface, a defensible network, a hard science. They are the batch’s hedge against its own thesis.
Who got in, and what it says
Lu also pulled the background of all 395 founders, and one number reframes the romance of the AI founder. The most common prior employer is not a frontier lab — it is Amazon, with 33 founders, ahead of Meta and Google/DeepMind at 17 apiece.
| Founder signal | Figure | What it says |
|---|---|---|
| Most common prior employer | Amazon (33) | operators, not researchers |
| Next: Meta / Google·DeepMind | 17 each | big-tech engineers, not lab alumni |
| Technical founders | 70% | builders by default |
| All-technical founding teams | ~50% | ship-first cultures |
| Hold a PhD | 5% | the genius-researcher myth |
| Dropped out to start the company | 3% | the dropout myth |
This is an operator’s batch, not a researcher’s: 70% of founders are technical and half of all companies have an all-technical founding team, but only 5% hold a PhD and only 3% dropped out to start the company. The dropout-genius myth is, statistically, a myth. The modal S26 founder is an engineer who shipped real systems at scale at a large company and left to point an agent at a job they watched humans do badly.
That profile is the human form of the thesis. You do not need a novel model to build a vertical agent — you need to know, in operational detail, how a specific business actually runs, so your agent can do the work rather than describe it. The batch selected for people who have seen the inside of the job. It is a reasonable bet on who wins an execution war. It is not a bet on who invents the next breakthrough, because the batch has decided the breakthrough already happened and the work now is distribution.
The wager underneath
Strip the batch to one sentence and it reads: the agent works, the thesis is proven, and the only variable left is who ships fastest into which vertical. Every structural number supports it — the 70% building agents, the 86 building the same shape, the operators leaving Amazon to do it, the venture firms confirming it from the outside.
The risk lives in the same sentence. A batch that has resolved the technology question down to execution is a batch that has conceded the technology is not defensible. The winners will be the teams that convert speed into the things speed can buy before the window closes — proprietary outcome data, signed enterprise logos, a vertical so deep no generalist can follow. The losers will be the ones who discover that “we build agents for X” was a description shared by fifteen other teams, and that being good at the same legible thing is not a business.
YC bet a decade ago that vertical agents would be 10x SaaS. Spring 2026 is that bet, placed 196 times. What the batch has not yet priced is that when the whole table reads the same thesis, the thesis stops being an edge and becomes the price of entry — and the edge moves to whoever owns something the thesis can’t copy.