On June 3, 2026, the venture firm Andreessen Horowitz published an essay arguing that the most overlooked market in artificial intelligence is the corner dental office, and on the same day wired the argument into two term sheets. The essay, titled “Small Businesses are the Next Frontier for AI,” carried a subtitle that doubles as a thesis statement: “Agents are ready to run Main Street and do the work nobody wants to do.” Hours later the firm announced it was leading a $35 million Series A for Lassie, a company that does the back-office work of dental practices, and a $55 million Series A for Town, a personal assistant. A day after that, a London startup called Airspeed closed $20 million to replace the software that sales teams use with agents that do the selling instead.
Read together, the week is a thesis being funded in real time. The argument is that the next great software companies will not sell small businesses better tools; they will do the businesses’ work. The pitch is sweeping and horizontal — the small business that runs itself. Every company being funded to deliver it is narrow and vertical. That gap, between the manifesto and the cap table, is the entire story.
The week, in dollars
The cleanest way to see the pattern is to line the rounds up by date. Three Series A rounds in roughly 72 hours, two of them led by the same partner at the same firm, all selling versions of the same promise.
| Company | Vertical | The pitch | Round | Lead | Valuation | Date |
|---|---|---|---|---|---|---|
| Lassie | Dental → SMB | ”AI that runs small businesses” — files claims, reconciles payments, bills patients | $35M Series A | a16z | ~$250M | Jun 3 |
| Town | Horizontal assistant | A personal AI assistant across email, calendar, docs, that acts proactively | $55M Series A | a16z + Forerunner | not disclosed | Jun 3 |
| Airspeed (ex-Glyphic) | Sales / revenue | An agent-native “commercial brain” that replaces CRM dashboards | $20M Series A | DN Capital | not disclosed | Jun 4 |
The double-header drew immediate notice from the people who watch funding for a living. Alex Konrad, who covers startups at Upstarts Media, flagged the unusual shape of it:
Rare to see two big Series A funding rounds, led by the same investor, announced on the same day 👀 Alex Rampell (@arampell) at @a16z just led: ▪️$35M in Lassie (AI for dental offices) ▪️$55M in Town (AI assistants) Busy times in the AI app layer if you’ve got the funds…
— @alexrkonrad Jun 3, 2026
Lassie’s own announcement was the loudest. The launch post from co-founder Steijn Pelle became the highest-engagement item of the week by a wide margin, and it stated the claim in the plainest possible terms:
Today, we’re introducing Lassie and $47M in funding led by a16z. We’re building AI that runs small businesses, starting with doctors’ offices. Lassie is already trusted by 700+ practices across the country, working autonomously to provide them with 30 hours of labor per month.
— @steijnpelle Jun 3, 2026
There is a small discrepancy worth marking, because it recurs across the coverage. The founder cites “$47M in funding,” the company’s cumulative total, while a16z and the trade press report a $35 million Series A at a roughly $250 million valuation. Both are accurate; they measure different things. The number that matters for the thesis is the traction: a16z’s memo states Lassie “works with more than 700 practices across 49 states, generates more than $10 million in annualized revenue, and provides practices with 250,000 hours of labor a year.” That is not vaporware. It is a real company with real revenue, growing largely by word of mouth.
The thesis: stop selling the tool, sell the work
The intellectual frame underneath the checks is not new, and a16z is not the only firm running it. The clearest statement of it came three months earlier from Sequoia’s Julien Bek, in an essay titled “Services: The New Software.” Its central claim is a multiples argument dressed as a prediction:
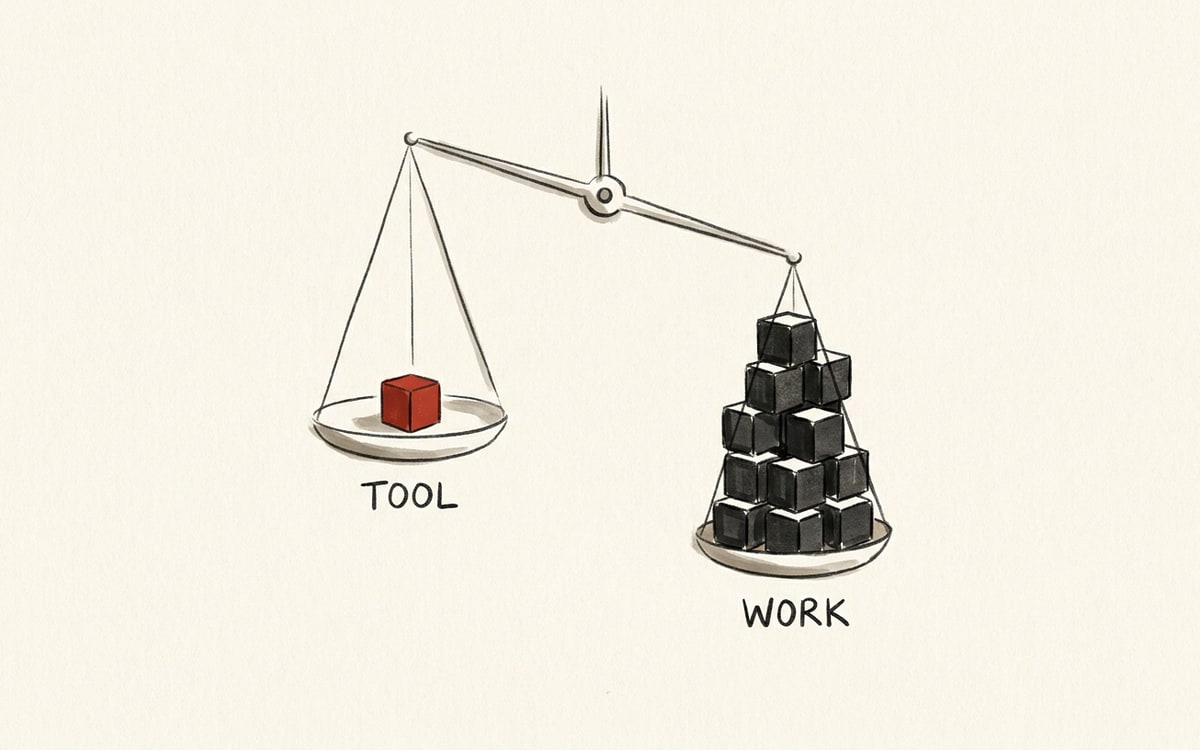
If you sell the tool, you’re in a race against the model. But if you sell the work, every improvement in the model makes your service faster, cheaper, and harder to compete with. A company might spend $10K a year for QuickBooks and $120K on an accountant to close the books. The next legendary company will just close the books.
— Julien Bek, Services: The New Software, Sequoia Capital, Mar 5, 2026
Bek’s compression of it, “a copilot sells the tool, an autopilot sells the work,” is the same bet a16z is making in different words. In the Lassie memo, the partners write that “the last generation of software gave businesses better tools” and that “AI agents change the unit of value from software to labor.” The accountant’s $120,000 in Sequoia’s example and the “$200,000 a year on staff” a16z cites for a medical office are the same figure: the work budget, which in any profession dwarfs the tool budget, and which software has historically never been able to touch.
Both firms are, in turn, drawing on a16z’s own earlier work. In February 2025, a16z’s Kimberly Tan published “Unbundling the BPO,” arguing that the business-process-outsourcing market, over $300 billion of human labor arbitrage, was the real prize AI would capture by selling the output rather than the seat. The line from “Unbundling the BPO” to “the unit of value moves from software to labor” is direct. What changed between 2025 and June 2026 is that the firm now has companies with revenue to point at.
The emotional core of the pitch is a character a16z keeps returning to: the reluctant operator. The Lassie memo opens with it, and Pelle’s essay makes it the protagonist.
Most are reluctant operators: doctors want to help patients, the plumber wants to fix your sink, and the manicurist wants to do your nails. The paperwork is the last thing they want to spend time on. Until now, software has not removed this work; it merely rearranged it. It gives you a dashboard, a queue, a form, and maybe a better place to click. But someone still has to click.
— Steijn Pelle, Small Businesses are the Next Frontier for AI, a16z, Jun 3, 2026
It is a good argument, and the “someone still has to click” line is the sharpest critique of the last fifteen years of SaaS in a single sentence. The investor voice on the deal stated the destination without hedging:
Excited to announce @a16z is leading @lassieai’s Series A! (@arampell) Lassie is building AI that can run small businesses - starting in dental They’re already generating more than $10M in annualized revenue, and helping 700+ practices 👇
— @omooretweets Jun 3, 2026
The horizontal pitch, the vertical reality
Here is where the manifesto and the portfolio diverge. The pitch is always horizontal — “the small business that runs itself,” “AI that can run small businesses,” Main Street. But every company that has reached fundable revenue is a specialist, and the specialization is not incidental. It is the entire reason any of them work.
Pull back from the June rounds to the broader 2026 cohort, and the pattern is total.
| Company | Vertical | Funding | Lead | Valuation |
|---|---|---|---|---|
| Lassie | Dental admin | $35M Series A | a16z | ~$250M |
| Basis | Accounting / tax | $100M Series B | Accel + GV | $1.15B |
| Avoca | Home services (HVAC/plumbing) | $125M+ | Meritech + General Catalyst | $1B |
| Nory | Restaurants | $37M Series B | Kinnevik | n/d |
| Endex | Finance (Excel) | $14M | OpenAI Startup Fund | n/d |
| Spellbook | Legal contracts | $50M Series B | Khosla | ~$350M |
| Toothy AI | Dental insurance | YC W25 | Y Combinator | n/a |
There is no horizontal company on this list except by aspiration. Basis closes the books and files returns — it is an accounting firm. Nory forecasts demand and runs payroll for restaurants. Avoca answers the phones for HVAC and plumbing companies. Endex lives inside Excel for banks and hedge funds. Each one picked a single trade, learned its specific workflows, and built the integrations that make autonomy possible in that trade and nowhere else.
The most candid acknowledgment of this comes from a16z itself. The same memo that promises “the small business that runs itself” spends its defensibility section explaining why the company is hard to copy, and the explanation is an argument for verticalization:
This is also why Lassie is difficult to replicate with a generic model alone. Running a small business is not one task; it is thousands of recurring workflows… Over time, the product learns from every completed workflow, building a knowledge layer that is difficult to recreate from scratch.
— Alex Rampell & Olivia Moore, Investing in Lassie, a16z, Jun 3, 2026
Read that closely. The moat exists because Lassie went deep on dental’s thousands of specific workflows. By the same logic, a horizontal “any SMB” agent, one that has not done the years of schlep in any particular trade, would have no moat at all. The horizontal pitch and the defensibility argument are in direct tension. The thing that makes Lassie investable is precisely the thing the headline promise glosses over.
This is not a new lesson. The historical winners in small-business software were vertical to the bone: Toast for restaurants, ServiceTitan for the trades, Procore for construction, Clio for law firms. The horizontal tools that did win, QuickBooks and Square, each captured a single function (the books, the payments) and never the whole business. A founder watching the Lassie round named the precedent and the risk in one breath:
The reluctant operator is the best B2B customer type there is. High WTP, low churn, clear ROI. Clio proved it for lawyers, Jane for wellness. The real question for Lassie is whether they can build a moat before Dentrix or the DSO platforms decide to copy the feature set.
— @DevaBuilds Jun 3, 2026
The venture data backs the vertical read. The aggregator AgentMarketCap, tracking the thesis shift across firms, found that “wrapper startups”, the horizontal, thin, model-dependent kind, were being assigned 3–5x revenue multiples, while companies “building foundational models or agentic systems for specific verticals now command 40–50x revenue multiples.” Its sharpest finding: in 2024, horizontal AI companies out-raised vertical ones, $1.6 billion to $1.2 billion. “That gap inverted within twelve months.” The capital is voting for vertical even as the marketing speaks horizontal.
The argument over one word: runs
The market did not split on whether the wedge is real. It split on the verb. When the announcement said Lassie “runs” small businesses, the sharpest pushback came not from AI skeptics but from people who build in the space and think the word is doing too much work. The most direct rebuttal was a reply to the a16z partner’s own announcement:
Congrats to Lassie on the Series A, but 700+ practices and $10M in revenue from AI alone is a far cry from running small businesses.
— @Prithvi_Jadwani Jun 3, 2026
The more useful critique reframed the product entirely — not as autonomy, but as the removal of specific, boring, money-losing tasks. This is a bull case for the business and a bear case for the language:
This is the right market shape. Dental is not cute “AI employee” stuff; it is claims, payments, staffing, cash flow. I’d sell the owner one fewer forgotten back-office task, not autonomy. Small businesses buy relief from boring leakage.
— @Timur_Yessenov Jun 4, 2026
“Relief from boring leakage, not autonomy” is the most precise description of what these companies actually sell, and it explains the engagement gap between the marketing and the skeptics. The owner of a dental practice does not want to manage an “army of AI employees”; the owner wants the insurance claims filed correctly and the payments reconciled so nothing leaks. That is a deep vertical product. Calling it “the business that runs itself” is the part the practitioners flinch at.
There is a maximalist camp that takes the horizontal claim at face value, and it is worth representing fairly, because it is the bet a16z is underwriting:
This is the ultimate business solution for a small business. “Go serve your customers, it’ll handle the rest.” Everything else, all SaaS apps a small business would use otherwise, can be abstracted away with this. Only way to build this - learn the business like you’d run it.
— @RamXChoudhary Jun 3, 2026
Notice that even the maximalist case ends on a vertical instruction: “learn the business like you’d run it.” You cannot learn every business that way. The dream is horizontal; the only known method of building it is one trade at a time.
The structural risk nobody on stage mentions
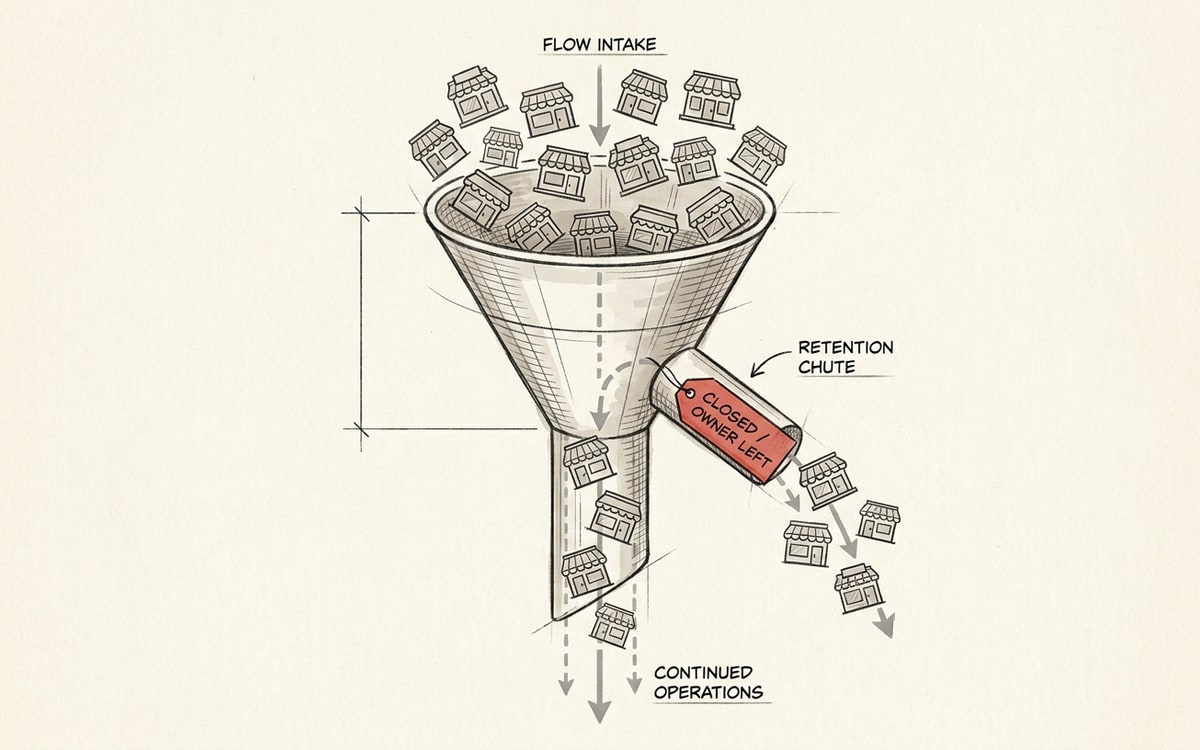
The bull case rests on Lassie’s real traction. The bear case rests on a number that has nothing to do with how good the AI is, and everything to do with who the customer is. Small businesses are, historically, the worst software customers in existence.
SMB SaaS churns at roughly 4.5% a month — about 42% a year, against 1–2% annually for enterprise. And the leading cause is not fixable by any product team. The single largest reason small businesses stop paying for software, at 32% of churn, is that the business closed or the owner exited. Small-business mortality itself caps retention. You can build a flawless dental agent and still lose a third of your churn to dentists retiring, selling, or shutting down.
This is why a16z’s own go-to-market concedes the difficulty, and why Pelle’s essay leans so heavily on a tactic that is hard to scale: the founders installed the product in person, in the first hundred practices, after working inside dental offices for months reconciling payments and filing claims themselves. It is a moving story and a real moat. It is also a founder tactic, not a scaling model. The open question the June rounds do not answer is whether door-to-door, white-glove onboarding survives the jump from a hundred dental practices to the half-million doctors’ offices — let alone to “any small business.”
The practitioners who build these systems have already located the real failure mode, and it is not capability. It is accountability. On a thread asking whether anyone is actually making money selling agents to local businesses, the sharpest comment cut past the technology entirely:
I don’t think the main question is whether the agent is “good enough”. The main question is whether the business owner can tolerate a failure mode they can explain to a customer.
— r/AI_Agents, Is anyone actually making money selling AI agents to local small businesses?, 2026
That comment also contains the strongest argument for the vertical approach: the same builder noted that “dental booking and WhatsApp ordering both have real APIs underneath, so they’re maintainable.” Reliability is a function of how structured the workflow is, which is a function of how deep into one vertical you have gone. The failure modes cluster in unstructured edge cases — menu drift, pricing changes, the exception the model has not seen. Depth is the fix. Which is, once again, an argument for vertical and against horizontal.
What the bet actually is
Strip away the manifesto language and the bet a16z placed in the first week of June is narrower and more interesting than “AI will run Main Street.” It is this: that a company can win one vertical with founder-installed, work-replacing agents, build a proprietary workflow knowledge layer that generic models cannot copy, and then, in the leap that matters, repeat the playbook across enough verticals fast enough to become horizontal by accumulation before the SMB-churn tax and the commoditizing agent-framework layer underneath catch up.
Lassie’s $10 million in annualized revenue says the first part is working in dental. The vertical winners across accounting, restaurants, home services, and legal say the playbook ports. The 42% annual churn and the in-person onboarding say the repetition is going to be expensive and slow. Nothing in the June rounds resolves the tension; the checks are a wager that depth compounds faster than mortality erodes.
The founders, to their credit, are not really selling the horizontal dream when they talk to each other. They are selling the wedge.
Small businesses have been overlooked. There is a great AI company to be built.
— @steijnpelle Jun 3, 2026
A great AI company, singular, built one trade at a time. That is the honest version of the thesis, and it is a better one than “the business that runs itself.” The reluctant operator is, as the venture firms have correctly identified, an excellent customer — high willingness to pay, clear return, work worth removing. The question the next eighteen months will answer is not whether an agent can do a dentist’s billing. Lassie has already shown it can. It is whether “Main Street” is a market you can win, or only a sequence of small, deep, unglamorous trades you have to win one by one, faster than the owners close up and leave.