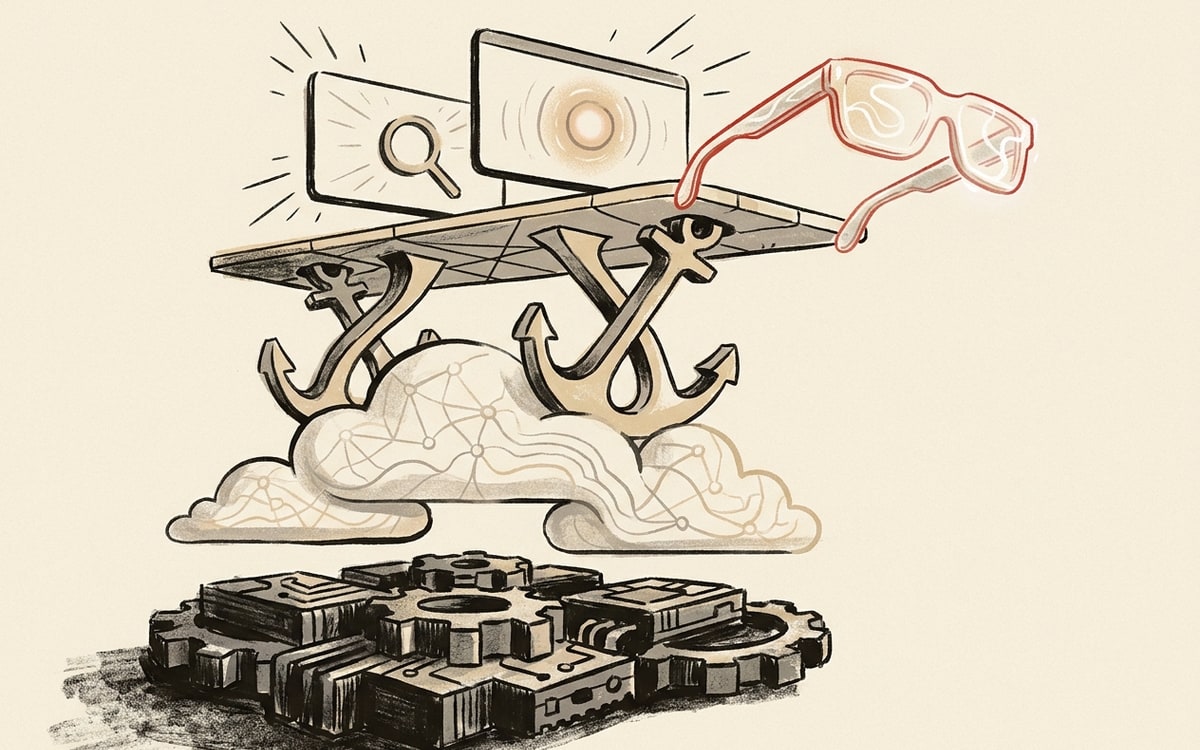
At 17:00 UTC on May 19, 2026, Sundar Pichai walked onto the Shoreline stage and opened Google I/O ‘26 with a number nobody else in the industry can match: 3.2 quadrillion tokens per month flowing through Google’s models. Two years ago that number was 9.7 trillion. Last year at I/O it was 480 trillion. Today’s number is a 7× year-over-year jump and a 330× jump in 24 months.
Two hours and fifty-seven minutes later, the keynote had landed eight first-class platform shipments, a new model family, a new dev environment, a new chip generation, a new search experience, a new hardware partnership, and a $5 billion joint venture. The full playlist (with the keynote, the ASL keynote, and seven short promos) sits at 9 videos and ~9M cumulative views in four hours. The keynote alone hit 8.4 million views and 21,631 likes in the first window.
It also did not ship Gemini 3.5 Pro — and the absence of that single model is now the load-bearing reason the X discourse is mixed.
This is the audit. Every claim traces to a verbatim keynote pull, a Google blog post, a sourced tweet, or the official product page. We pulled the entire 2:57 transcript, harvested 30+ I/O 2026 blog posts, ran six structured queries against the xAI Agent Tools API to capture the X discourse, and read every named primary doctrine speaker on stage. The post is long because the keynote was wide. Scroll, search, or read straight through — the index runs in order of importance, not order of stage time.
The opening: the 3.2 quadrillion number, the 13 billion-user products, the 900M Gemini app
Sundar started with the framing that has now become Google’s master narrative for the entire AI moment. Verbatim from the keynote (67:15 mark):
“Ten years since we pivoted the company to be AI-first… This is why we are taking a differentiated, full-stack approach to AI innovation. From our custom silicon and secure foundation, to our world-class research and models, to our products and platforms that reach billions of people. This approach enables us to iterate and innovate faster, and it’s lighting up every part of the company.”
— Sundar Pichai, Google I/O ‘26 keynote, May 19, 2026
Then the numbers landed in sequence:
| Metric | Value | Year-over-year context |
|---|---|---|
| Tokens processed per month | 3.2 quadrillion | 480T at I/O ‘25 → 7× growth |
| Developers building on Gemini API monthly | 8.5 million | First public number this large |
| Model API tokens per minute | 19 billion | Steady-state load |
| Customers each processing >1T tokens in last 12 mo | 375 | New disclosure |
| Google products with >1B users | 13 | of which 5 have >3B users |
| AI Overviews monthly users | 2.5 billion | The base for AI Mode |
| AI Mode monthly users | 1 billion in 1 year | Sundar: “a revelation, our biggest upgrade to Search ever” |
| Gemini app MAU | 900 million | from 400M at I/O ‘25 (+2.25×) |
| Gemini app daily requests YoY | +7× | (over 12 months) |
| Nano Banana images generated | 50 billion | (cumulative since launch) |
These are not vanity metrics. The 3.2 quadrillion / 480 trillion / 9.7 trillion sequence is what justifies the $180–190 billion 2026 capex line Sundar would announce nine minutes later. The 900M Gemini app users is what makes the Spark agent (announced 20 minutes later) a credible distribution play. The 13 billion-user products is what turns Antigravity into the IDE that has built-in access to those products — not as integrations, but as primitives.
A reply to Sundar’s launch thread caught the right framing:
“Google is moving from Search to Execution… Agentic Commerce: AP2 & UCP protocols. AI now monitors price drops and handles secure purchases. The ‘User Interface’ is being replaced by Intent.”
— @SahilPanhotra May 19, 2026
That’s the entire keynote in one tweet. Search is becoming Execution. The model is becoming the agent. The agent is becoming the app. The distribution-times-tokens flywheel is becoming the company.
Gemini 3.5 Flash — and the Pro that didn’t ship
The first major model announcement was Gemini 3.5 Flash, available today across every Google surface and the API. The headline benchmarks (per the Google DeepMind blog):
| Benchmark | Gemini 3.5 Flash | Reference |
|---|---|---|
| Terminal-Bench 2.1 | 76.2% | Agentic terminal tasks |
| GDPval-AA | 1656 Elo | Multi-step agent benchmark |
| MCP Atlas | 83.6% | MCP tool-call benchmark |
| CharXiv Reasoning | 84.2% | Multimodal chart reasoning |
| Output speed | ~4× faster than other frontier models | Per Artificial Analysis |
| Price | <50% of other frontier models | Per Sundar’s stage line |
The pitch, verbatim from the keynote (88:11):
“Today I’m thrilled to introduce Gemini 3.5 Flash, our latest model… It outperforms 3.1 Pro on coding and agentic benchmarks while running four times faster than other frontier models, providing the high-speed engine needed for real-world agentic workflows.”
— Sundar Pichai, I/O ‘26 keynote, May 19, 2026
The dataset Sundar then dropped was the operational kicker:
“In March, we were processing half a trillion tokens a day internally for our developers. We’ve been doubling every few weeks. And now, we are processing more than 3 trillion tokens a day.”
— Sundar Pichai, I/O ‘26 keynote (89:55)
3 trillion internal developer tokens per day. This is the number Google is using to explain why 3.5 Flash is good — the internal feedback loop has compounded faster than anything an external model can replicate.
🔴 What didn’t ship is what dominated the X criticism. The blog post says it plainly:
“We’re also hard at work on 3.5 Pro. It’s already being used internally, and we look forward to rolling it out next month.”
— Gemini 3.5 launch post, May 19, 2026
The most-engaged critical tweet of the day articulated the gap:
“I am genuinely disappointed that Google hasn’t been able to launch a frontier model at I/O. Some cool new features have been launched for sure but it has been a WHILE since Google was on top of the leaderboard. Pretty disappointing. Claude is still firmly ahead. By a lot.”
— @RudyReaper May 19, 2026
And the cleanest summary of the leaderboard problem:
“gemini flash 3.5 looks pretty neat and extremely fast but still largely the sort of incremental progress we’ve come to expect from google. generally a pretty disappointing IO.”
— @tenobrus May 19, 2026 (116 likes — highest-engagement criticism of the day)
The leaderboard read is fair. The product read isn’t quite the same. A Flash model that’s better than last year’s Pro at 4× the speed and half the cost is the right product for an agentic world — because agentic workflows are bound by latency and unit cost, not by peak benchmark Elo. Sundar made that argument with one specific Antigravity demo we’ll get to in the next section. The market gets to decide whether that’s enough.
The deployment surface is wide:
- Gemini app: 3.5 Flash is now the default model globally (900M MAU)
- AI Mode in Google Search: 3.5 Flash is the default (1B MAU)
- Antigravity 2.0: 3.5 Flash is the primary developer model
- AI Studio + Android Studio: SDK access via the Gemini API
- Gemini Enterprise Agent Platform: Enterprise tier
- Shopify is running subagents in parallel for merchant growth forecasts (per the blog)
This isn’t a model release. It’s a default-model swap across every Google surface in one stroke.
Antigravity 2.0 — the developer announcement that matters most
If you had to pick one announcement from I/O ‘26 to bet your dev career on, it’s Antigravity 2.0. Varun Mohan opened the developer segment with the strongest single line in the keynote:
“It’s truly an amazing time to be a builder. We’ve moved beyond AI tools that help us write, to agents that help us act.”
— Varun Mohan, I/O ‘26 keynote, May 19, 2026
The shape of Antigravity 2.0:
| Surface | What it is | Replaces |
|---|---|---|
| Standalone desktop app | Native agent-first development environment | The November 2025 Antigravity IDE extension |
| CLI | Terminal-native agent surface, same harness | Gemini CLI (sunsets June 18, 2026) |
| SDK | Programmatic access to the same agent harness Google uses internally | (new — no prior equivalent) |
| Managed Agents in Gemini API | Single API call returns an agent in an isolated hosted Linux VM | (new — Google now operates the agent runtime) |
| AI Studio integration | One-click export from AI Studio prototype to Antigravity project | (new) |
| Native Android development | Build Android apps with Jetpack Compose + Kotlin in AI Studio + Antigravity | (new) |
The internal demo Varun showed is the load-bearing proof point. Quoting the keynote (93:10):
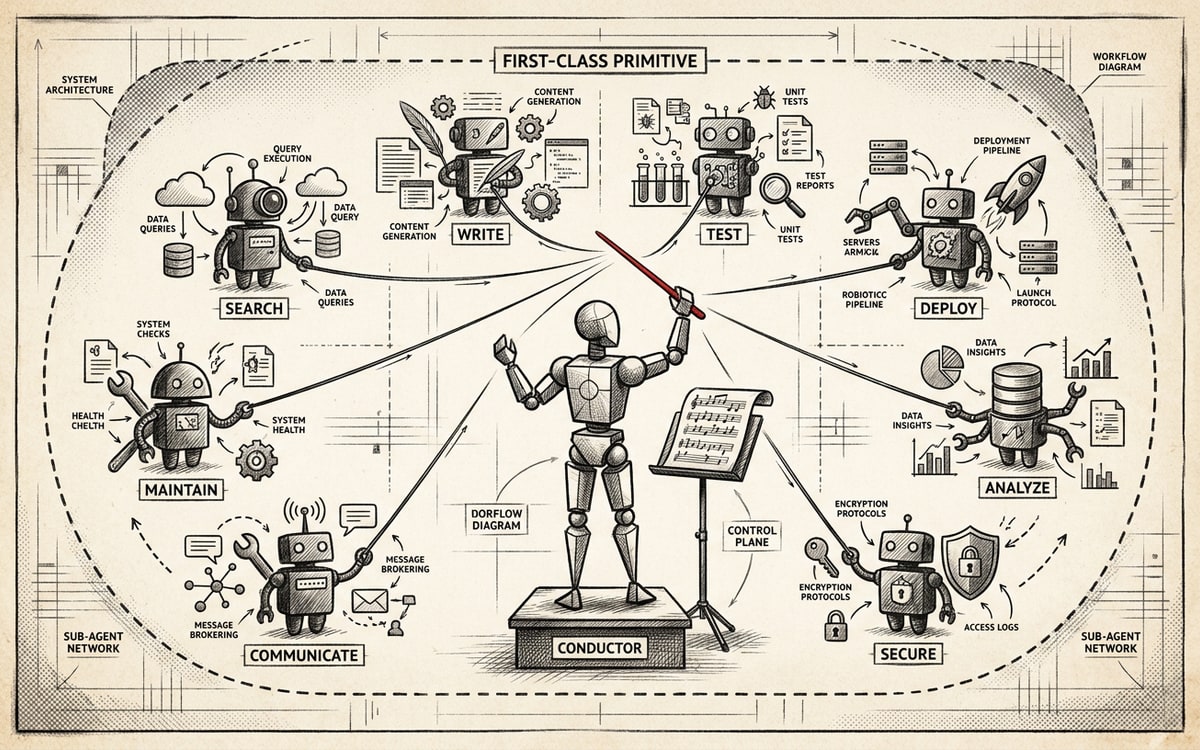
“Asynchronously, Antigravity broke down the challenge into a cohesive plan, tackled tasks via parallel subagents, generated, executed, and iterated over its very own tests. Over 12 hours, 93 subagents working in parallel made over 15,000 model requests and processed 2.6 billion tokens to take an initially empty project to the core of a functioning operating system.”
“This was not possible on Gemini 3.1 Pro, but thanks to the performance and cost efficiencies of Gemini 3.5 Flash, building an entirely functional operating system consumed less than $1,000 of API credits.”
— Varun Mohan, I/O ‘26 keynote, May 19, 2026
🟢 The numbers to internalize: 93 subagents in parallel, 15,000 model requests, 2.6 billion tokens, 12 hours, <$1,000. That’s ~$0.385 per million tokens at the bundle level for an autonomous agent swarm, including all the failed paths the swarm took. That’s the price Google is implicitly pricing Antigravity at.
The X reaction from independent voices read this as a category move:
“This isn’t a Gemini feature — Google is going after the entire AI dev environment.”
— @souen3632 May 19, 2026
The competitive map this lands in:
| Competitor | What they ship | Where Antigravity 2.0 is ahead | Where Antigravity 2.0 is behind |
|---|---|---|---|
| Cursor | Editor with AI sidebar | Multi-agent orchestration as first-class concept; standalone app, not VSCode fork | Cursor’s editor experience is more polished; tighter Tab UX |
| Claude Code | Anthropic’s CLI agent | Same shape; Google ships GUI + CLI together; Managed Agents API (Anthropic doesn’t host runtimes) | Claude’s coding quality on benchmarks remains the reference |
| Replit + Replit Agent | Browser IDE + hosted runtime + agent | Antigravity’s harness is shared with Google’s own internal use (battle-tested) | Replit owns the “no local install” experience |
| Firebase Studio | Google’s prior agentic IDE | Antigravity 2.0 is the successor — Firebase Studio is being repositioned around backend | n/a |
| OpenAI Codex CLI / Builder | OpenAI’s coding shells | Antigravity ships with the harness; Codex still ships primarily as a model + thin CLI | OpenAI’s distribution among developers (via ChatGPT) is wider |
| GitHub Copilot Workspace | Microsoft’s agentic IDE | Antigravity has multi-subagent orchestration; Workspace is single-thread | Microsoft owns the GitHub integration surface |
The Managed Agents API is the part the competitive map doesn’t capture. Quoting the @Google launch tweet:
“We’re giving you access to the exact same Antigravity agent harness we use at Google. Introducing Managed Agents in the Gemini API. In a single API call, you get the agent and a secure, hosted Linux environment — we handle the infrastructure so you can focus on the user experience.”
— @Google May 19, 2026
🔴 This is the real competitive shift. Anthropic does not host agent runtimes (Claude is a model). OpenAI’s Agent Builder is opinionated and locked to OpenAI’s surfaces. Cursor doesn’t run a runtime. Google now does — and the runtime is the same one Google uses on Google.
Pricing is the rough edge. Antigravity 2.0 is gated behind Google AI Ultra at $100/month (the new mid-tier that landed today) and $200/month at the top tier (which dropped from $250). The mid-tier gives 5× higher Antigravity usage than the $20 Pro plan; the $200 tier gives 20× higher. Google is also handing out $100 in bonus credits expiring May 25, 2026 — a fast on-ramp before the bills start.
The pricing model also shifted under everyone today, quoted from the subscriptions blog:
“We’re moving from daily prompt limits to a ‘compute-used’ model. These new, compute-based usage limits in the Gemini app factor in the complexity of your prompt, the features you use and the length of your chat… If you reach your cap on our biggest models, we’ll shift you to our state-of-the-art, lightning-fast smaller models so you never miss a beat.”
Translation: Google is metering by compute, not by prompt count. The 3 trillion tokens/day internal developer load is the floor; the metering tells us where the ceiling is.
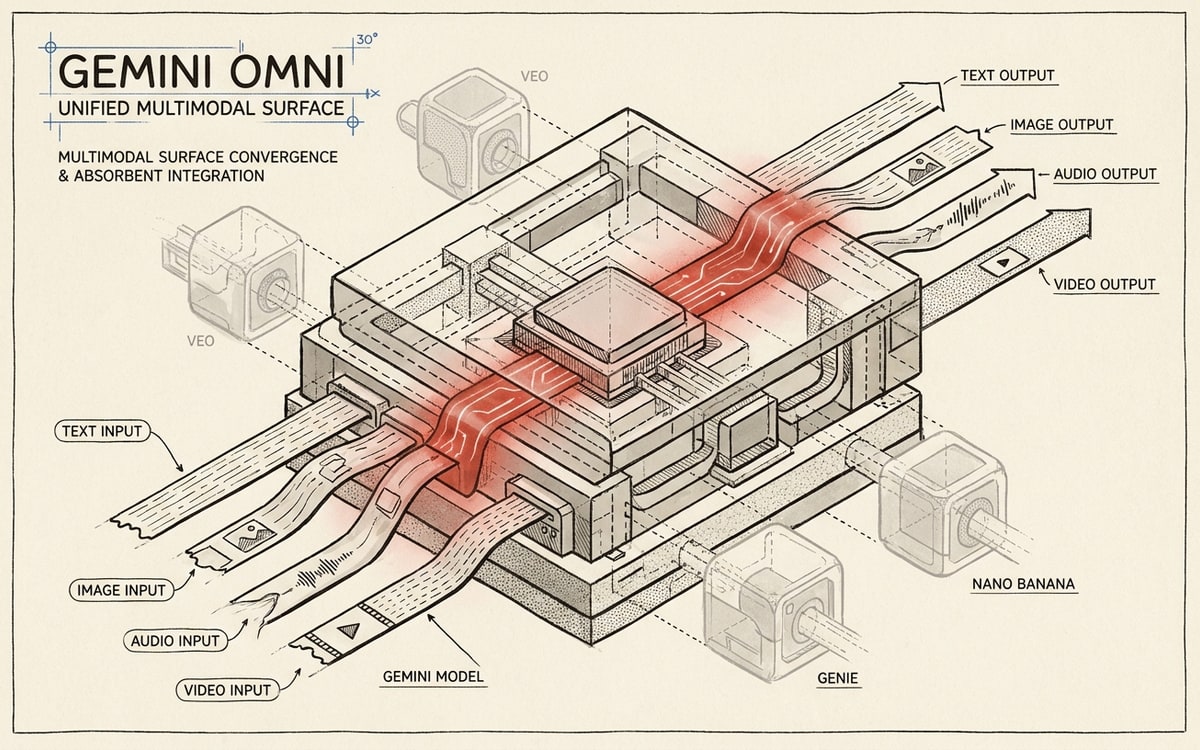
Gemini Omni — the unified multimodal model
The second major model launch was Gemini Omni, which Demis Hassabis introduced on stage. Verbatim (82:17):
“Our new model that can create anything from any input. It combines Gemini’s intelligence with the best of our generative media models for a new level of world understanding, multimodality and editing. Models like Veo, Nano Banana and Genie are able to create extremely realistic videos, images and interactive simulations. Although not perfect, they already demonstrate some impressive notions of intuitive physics. And with Omni, we’ve now made even more progress. It’s a step-change in simulating things like kinetic energy and gravity. Previous systems would have found these concepts difficult.”
— Demis Hassabis, I/O ‘26 keynote, May 19, 2026
The deployment shape:
- Gemini Omni Flash ships today across Gemini app + Google Flow for AI Plus/Pro/Ultra subscribers globally
- YouTube Shorts integration rolls out this week
- API access rolls out to developers + enterprise “in the coming weeks”
- Omni Pro “coming soon” (this is the larger model; Flash is the cheaper variant)
- Avatars ship as a first-party feature: generate video with your own voice
- Every output carries an invisible SynthID watermark (the 100B-watermarks-since-launch count is now the de facto industry baseline)
The 36-second demo embedded in the keynote was the centerpiece. The official launch tweet hit the highest engagement of the entire day:
Paraphrase: @GoogleDeepMind framed Gemini Omni as a first step toward a model that can create anything from anything, starting with video, combining Gemini’s intelligence with generative media systems and positioning it as a leap in world understanding, multimodality, and editing.
— @GoogleDeepMind May 19, 2026 (5,194 likes · 439K views, paraphrased)
Demis’s follow-up framed the long arc:
“Gemini Omni is a major leap in world understanding & multimodal editing! It can take photos, video & audio and build entirely new scenes. Over time it’ll be able to handle any input & any output - starting w/ video. You can even give it your own videos & iterate on your ideas.”
— @demishassabis May 19, 2026
The product taxonomy this implies is important. Veo is the specialized video model; Imagen is the specialized image model; Nano Banana is the specialized edit-and-iterate image model; Genie is the specialized interactive-simulation model. Gemini Omni is the unified model that absorbs the conceptual surface of all of them into a single API call. Grok caught this distinction cleanly:
Gemini Omni replaces Veo in the Gemini app — Veo is the specialized model, Omni is the unified multimodal that does video, image, and (soon) audio generation natively.
— @grok May 19, 2026 (paraphrased)
The Sora comparison is implicit. Sora is OpenAI’s specialized video model. Gemini Omni’s pitch is that you don’t have to leave the Gemini app to get the same shape, with one critical addition: you can iterate on your own videos with a chat interface. That’s a Nano Banana pattern lifted to video. Reading the Omni-vs-Veo trade is the same shape as reading the Nano Banana-vs-Imagen-3 trade was last year: the unified model wins the integration story; the specialized model wins the headline benchmark. For the Gemini-app user — 900M of them — the integration story is what they touch.
TPU 8t and 8i — the dual-chip bet, the $5B Blackstone JV, and the $190B capex line
The infrastructure section was where Sundar made the strongest single argument of the keynote. Verbatim (76:34):
“In 2022, we were spending $31 billion annually in capex. This year, we expect that number to be about six times that, approximately $180 to $190 billion. A key part of this investment is our custom silicon. A decade ago, we announced our very first commercial tensor processing unit or TPU on this I/O stage. Since then, we have transformed how the industry builds for AI.”
— Sundar Pichai, I/O ‘26 keynote, May 19, 2026
The capex number is the single biggest disclosure of the day. $180–190 billion in 2026, up 6× from $31B in 2022, is now the published Google answer to the question “how seriously are you taking this?” For context, Microsoft’s 2026 capex is around $115B and Amazon’s is around $130B at the time of writing. Google has stepped to the front of the hyperscaler capex curve.
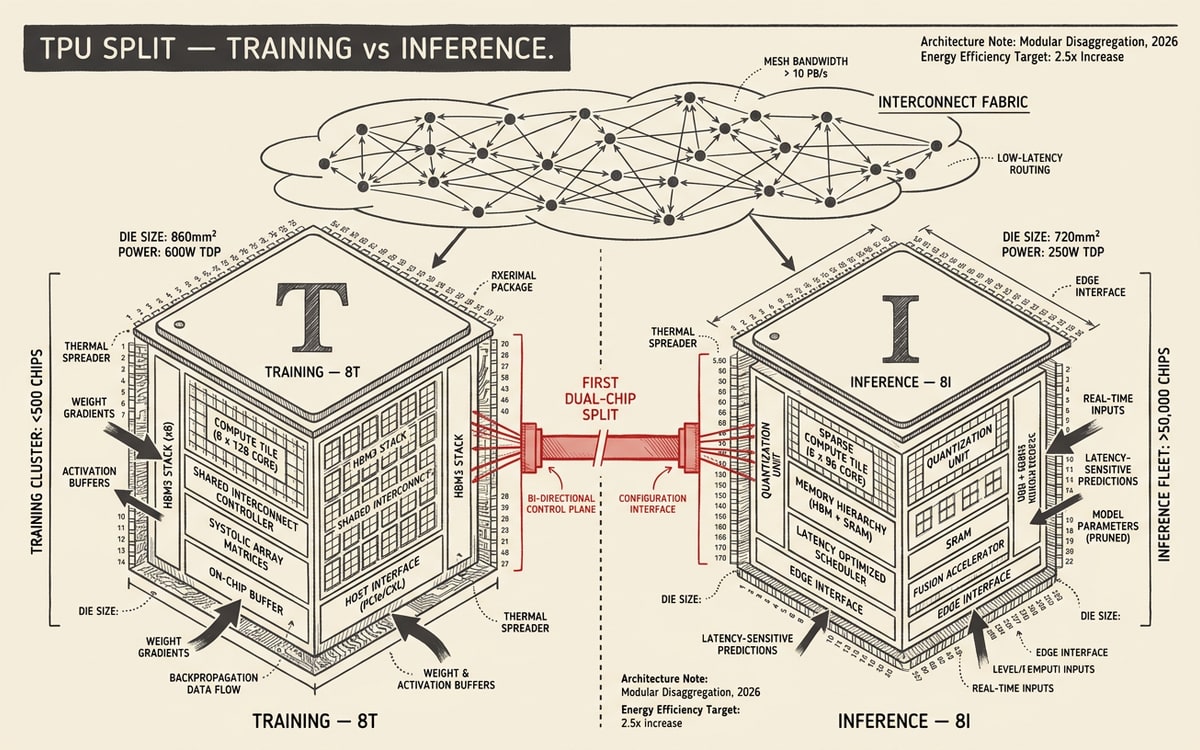
The chip story is the dual-chip bet — for the first time, Google split training and inference into two specialized SKUs:
| Chip | Optimized for | Key spec | YoY improvement |
|---|---|---|---|
| TPU 8t | Large-scale pretraining | Up to 3× raw compute vs. previous gen | ~2.7× perf/$ (training) |
| TPU 8i | Inference | ~1,500 tokens/s on a Flash prompt | ~1.8× perf/$, 2× perf/watt |
| TPU 8t superpod | Training cluster | 9,600 chips, 2 PB shared HBM, 121 ExaFlops | ~3× compute per pod |
| JAX + Pathways | Multi-site training | >1M TPUs distributed globally | ”Largest training cluster in the world” |
The JAX+Pathways disclosure is the part the competitive map will spend the next quarter digesting. Sundar’s verbatim:
“With JAX and Pathways, our training is no longer constrained by the limits of a single massive data center. Instead, we can now seamlessly distribute training across multiple sites, scaling across more than 1 million TPUs globally. This gives us the ability to create the largest training cluster in the world. For model builders, this means training larger, more capable models in weeks rather than months.”
— Sundar Pichai, I/O ‘26 keynote, May 19, 2026
Training across multiple data centers as a single logical cluster, over 1 million TPUs globally. That’s not a chip claim — that’s a software claim, and it’s the part Nvidia’s NVL72 racks cannot answer directly. The Blackwell side of the market still assumes a single data center per training run because the interconnect topology demands it. Pathways turns the WAN into the training fabric.
The financial reinforcement landed an hour later in a separate blog post:
“Today, Blackstone announced a joint venture with Google to create a new TPU cloud, giving customers more choice and flexibility in how they access cloud TPUs. Blackstone is making an initial $5 billion equity commitment to bring an expected 500MW of capacity online in 2027.”
🟢 The Nvidia-killer narrative is back on the table. TPU is no longer just an internal Google chip — it’s a chip Blackstone is willing to put $5B behind, with 500MW of capacity scheduled for 2027. Morgan Stanley’s note hit the wires within an hour citing this as the read-through for Nvidia.
🔴 The bear case landed within two hours, cleanly stated by Gavin Baker via the Alpha Podcast handle:
“TPU V8 made conservative design choices. Trainium made aggressive ones. The code is already written. H2 2026 will show it in ramp curves.”
— @podcast_alpha_x May 19, 2026
The investor framing on X was the cleanest single thread on TPU specs:
TPU 8t = 2.7× training perf/$, TPU 8i = 1.8× inference perf/$, both 2× perf/watt, $190B 2026 capex, JAX+Pathways scaling to millions of chips distributed across data centers.
— @DaveBlundin May 19, 2026
Read this against AWS Trainium 2, AWS Trainium 3 roadmap, and Nvidia Blackwell Ultra. The relative perf/watt and perf/$ numbers are close enough that Google is no longer at a structural disadvantage on either axis. The advantage Google does have is the vertical integration: the chip, the interconnect, the training framework, and the inference stack are all owned. Nvidia builds chips; AWS rents chips; Google ships the chip and the model and the IDE and the search box. That’s the moat the keynote was actually about.
Search — the box becomes an agent
The single biggest consumer announcement at I/O ‘26 isn’t a model or a chip. It’s the new Search box. The framing, verbatim:
“This is the next chapter of Google Search: intelligent AI that puts the world’s information to work for you.”
— Search at I/O 2026 launch post, May 19, 2026
And the standalone numbers:
- AI Mode at 1 billion monthly active users — in one year (the fastest-growing Google surface ever)
- AI Overviews at 2.5 billion MAU — the base layer
- 3.5 Flash is now the default model in AI Mode globally
- Multimodal inputs: text, images, files, videos, Chrome tabs
- Generative UI: Search builds custom mini-apps, dashboards, simulations on the fly
- Information agents: 24/7 background agents that find things on your behalf (Pro/Ultra subscribers, launching this summer)
- Agentic booking: extended to local experiences, services, beauty, pet care, home repair
- Agentic calling: Google’s voice agent makes phone calls on your behalf (select categories)
- Antigravity in Search: build custom mini-apps right in Search (“coming months”)
- Personal Intelligence: expanded to ~200 countries, 98 languages, no subscription required
The cleanest enumeration on X came from the SEO industry:
The intelligent Search box redesign is the biggest in 25 years — multimodal inputs (text, images, files, videos, Chrome tabs), AI Overviews → AI Mode continuity, Gemini 3.5 Flash as default.
— @aleyda May 19, 2026 (paraphrased)
Sundar’s launch tweet captured the agentic pivot:
“Gemini 3.5 Flash is transforming what you can do in Google Search with new agentic capabilities. A few things we’re introducing: A new intelligent AI-powered Search box, our biggest upgrade in 25 years — rolling out globally. New information agents that work in the background 24/7 to find exactly what you need at the right moment, and help you take action (coming this summer). And with the power of Google Antigravity, we’re unlocking new agentic coding capabilities, so Search can build custom interactive experiences – like visual simulations, dashboards or trackers – for your individual questions.”
— @sundarpichai May 19, 2026
🔴 The SEO and publisher implications are seismic. AI Mode at 1B MAU and Search-built-mini-apps as a primitive both break the link between the SERP and the publisher’s page for an even larger class of queries. The Antigravity-in-Search announcement is the most aggressive of all — instead of Google sending you to a publisher’s home-improvement comparison page, Google’s Search box will build you a comparison dashboard inline. The publishing industry’s response is going to be the second-loudest sub-story of the next 90 days.
The Gemini app — Spark, Daily Brief, Neural Expressive, MacOS
The Gemini app got a structural rebuild as a 24/7 agentic surface. Verbatim from the Gemini app blog:
“Gemini is becoming a more helpful AI assistant, with an intuitive new UI, proactive daily briefs and Gemini Spark, an agent to help you get things done around the clock.”
Six headline changes, in the order they appear on the launch page:
| Change | What it is |
|---|---|
| Gemini 3.5 Flash | Default model across the app globally |
| Neural Expressive | New design language — more emotional, more responsive UI |
| Gemini Omni | Multimodal generation built into the app |
| Daily Brief | Auto-generated morning briefing (Pro+) |
| Gemini Spark | Cloud-resident always-on agent (Ultra US first) |
| macOS app | Native desktop app at gemini.google/mac |
Spark is the load-bearing addition. Verbatim:
Spark “runs on Gemini 3.5 and uses the Antigravity harness. It’s deeply integrated with the Workspace tools you rely on daily, like Gmail, Docs, Slides. Because it is a cloud-based agent, Spark keeps working in the background even when you close your laptop or lock your phone.”
🟢 The architectural reuse is the read. Spark uses the same Antigravity harness the Cursor-competitor IDE uses. Google’s now deployed one agent harness across three completely different product surfaces — consumer assistant (Spark in the Gemini app), developer IDE (Antigravity 2.0), Search (Antigravity-in-Search agents). The harness is the platform. Internal MCP integrations announced with Spark on day one: Canva, OpenTable, Instacart.
The other consumer features got their own launch posts:
| Feature | What it is | Availability |
|---|---|---|
| Daily Brief | Personalized morning brief in the Gemini app | Pro+ subscribers, US first |
| Project Genie | The interactive simulation model that builds playable worlds | AI Ultra $200 tier, global |
| Gmail Live | Voice-driven Gmail conversational interface | Rolling out summer |
| Docs Live | Voice-driven document drafting | Rolling out summer |
| Keep Live | Voice “brain dump” → organized notes | Rolling out summer |
| AI Inbox | Gemini summarization across Workspace | Rolling out |
| Google Pics | New AI-edited photos surface | Rolling out |
| Ask YouTube | Conversational YouTube search | Rolling out |
The macOS app is shipping today. Spark and voice features arrive “later this summer.”
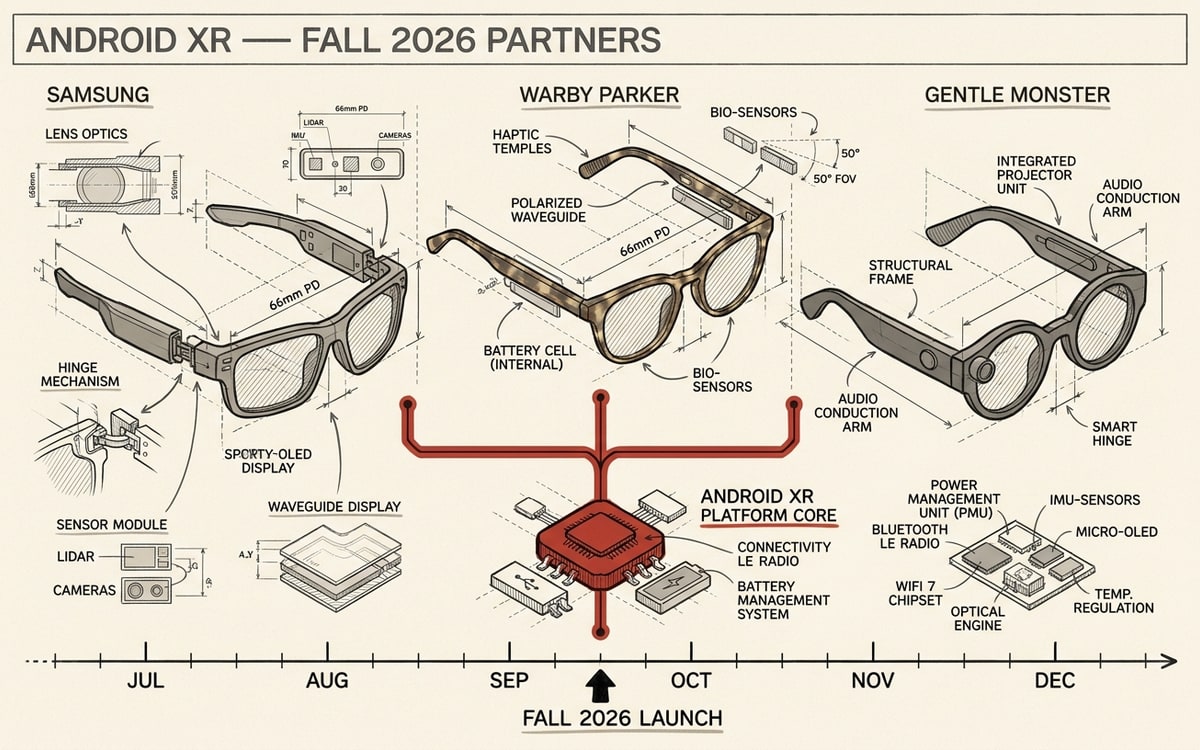
Glasses — Samsung, Warby Parker, Gentle Monster
The consumer hardware story landed with the loudest single non-AI-model engagement of the day:
“We’re partnering with @Samsung, @GentleMonster and @WarbyParker on new intelligent eyewear. Here’s a sneak peek at two designs from this fall’s upcoming collections.”
— @Google May 19, 2026 (1,648 likes · 139K views)
The shape:
| Tier | What it is | Partners | Ship date |
|---|---|---|---|
| Audio glasses | Spoken Gemini help in your ear, paired with Android and iOS | First wave this fall | Fall 2026 |
| Display glasses | In-lens display showing the relevant info as you ask | Coming later | TBD |
The choice to ship audio first is read-through worthy. Audio glasses are a shipping product the second they’re matched with a Gemini API that can hold a multi-turn conversation. Display glasses require new hardware and a new visual interaction language, which is harder. Google’s done the same thing Apple did with the Watch — ship the easier surface first, build the harder one toward a future drop.
Cross-platform support is the part the headline buries. iOS support is shipping on day one, which means Google isn’t locking this behind Android — it’s playing for the eyewear category itself, not the Pixel-tied form factor. Apple’s response is the second-loudest sub-story of the next 12 months, after the publishing one.
Agentic commerce — AP2, UCP, Universal Cart
The agentic commerce stack is the part of I/O ‘26 that operators should read most carefully. Verbatim:
“We’re building the foundation for agentic commerce, with updates including a new intelligent cart that brings superpowers to your shopping. People shop across Google more than a billion times a day, powered by advanced AI and the Shopping Graph — the world’s most comprehensive catalog of over 60 billion product listings.”
Three layers:
| Layer | What it is | What it standardizes |
|---|---|---|
| AP2 (Agent Payments Protocol) | The agent-side payment authorization protocol | How an agent presents and confirms a charge |
| UCP (Universal Commerce Protocol) | The merchant-agent contract layer | How a merchant exposes inventory + buying flow to any agent |
| Universal Cart | The unified cross-merchant cart | The first consumer surface that bundles multiple merchants in a single agent-driven checkout |
🟢 This is Google’s bid for the agentic-commerce standard the way Stripe is bidding for it on the payments side. Stripe Sessions 2026 in April shipped its MPP/UCP/x402 framework as Stripe’s answer. Google’s AP2+UCP is the answer from the demand side — Google has the 1B daily shoppers, the 60B-product catalog, and now the cart that bundles them.
The competitive reading from X caught the through-line:
“Search to Execution… AI now monitors price drops and handles secure purchases. The ‘User Interface’ is being replaced by Intent.”
— @SahilPanhotra May 19, 2026
The publishers’ problem from the AI Mode section now becomes the merchants’ problem. If your store doesn’t speak UCP, the agent doesn’t see your inventory. The protocol war for agentic commerce is now openly between Google’s AP2+UCP and Stripe’s MPP/UCP. Both will probably converge — and if they don’t, Amazon’s shape is to ignore both and build its own. We’ve been here before.
Gemini for Science — Hypothesis Generation, Literature Insights, Skills
The science segment is the part of I/O ‘26 that future Nobel laureates will cite. Verbatim from the Gemini for Science launch:
| Tool | What it is |
|---|---|
| Hypothesis Generation | Generates testable hypotheses given a literature corpus + research goal |
| Literature Insights | Synthesizes papers and surfaces cross-paper connections |
| Computational Discovery | Turns research goals into runnable code |
| Science Skills | A library of domain-specific Gemini skills (biology, chemistry, materials science) |
| Nature Papers Surface | Curated surface of recent Nature/Science/Cell papers with Gemini commentary |
The tweet that captured this:
“Introducing Gemini for Science — a collection of AI tools to help accelerate the scientific process. Gemini can already assist in solving complex problems, but our new @GoogleLabs prototypes can help streamline more daily scientific tasks, including: 📃 Staying on top of new papers · 🧑💻 Transforming research goals into usable code · 💡 Generating new hypotheses”
— @Google May 19, 2026
This won’t move the next quarter’s metrics. It might move the next decade’s drug pipelines. Anthropic doesn’t have a science suite. OpenAI doesn’t either. DeepMind is the only AI lab with a published Nobel-Prize-winning research line (AlphaFold), and that lineage is now in the consumer/enterprise product line as Gemini for Science.
What I/O ‘26 didn’t ship — the silences
The skill template requires a silences section. Here are the things the keynote did not address that builders will care about:
| Silence | Why it matters | Severity |
|---|---|---|
| Gemini 3.5 Pro | ”Coming next month.” This is the single largest source of X criticism. Until Pro ships, “we have a frontier model” is an asterisked claim. | 🔴 |
| Pricing for Antigravity beyond $100 Ultra | The Ultra tier covers individual builders. Team pricing, enterprise SLA, the per-seat-vs-per-agent model — all TBD. | 🔴 |
| Eval rigor for the Antigravity OS-from-scratch demo | The 93-subagent demo is impressive but uncited in any published eval. Reproducibility is asserted, not demonstrated. | 🟡 |
| What gets sunset at Google’s edges | Gemini CLI sunsets June 18, 2026. What about the dozen other Google AI products that overlap with Antigravity 2.0? Firebase Studio’s roadmap was sidelined. | 🟡 |
| Display-glasses ship date | ”Coming later.” The audio-glasses partnership is real for fall; the display product is still aspirational. | 🟡 |
| Detailed TPU pricing for the Blackstone JV | $5B / 500MW / 2027 are the press numbers. The price-per-TPU-hour for tenants, the SLA, the rental model — none of it is public yet. | 🟢 |
| MCP server count + ecosystem growth | Anthropic’s MCP launch in late 2024 has scaled to 97M SDK downloads. Google’s MCP integrations (Canva, OpenTable, Instacart) are first-party. No third-party server market mentioned. | 🟢 |
🟢 What the silences say: Google is launching breadth and trusting that depth will arrive on a quarterly cadence. The biggest single missing piece is the Pro model. The smallest is anything to do with the third-party ecosystem. The middle is everything to do with monetization edge cases.
The doctrine — six positions that repeat across the videos and blog posts
This is the analytical heart. Six positions land across the keynote, the 30+ blog posts, and the Sundar/Demis/Varun stage time. Each is concrete and falsifiable.
1. The token curve is the company
The 9.7T → 480T → 3.2 quadrillion sequence is the master metric. Verbatim from Sundar: “It tells an important story, about our products and how others are building on it as well, especially our developers.” Token consumption is the leading indicator Google is now using publicly to argue that its position in the AI race is improving, not eroding. If 3.5 Pro ships in a month and the curve holds, the Sundar argument compounds. If the curve breaks, the bear case from Gavin Baker on TPU and from @RudyReaper on models gets sharper.
2. Flash is the right shape for the agentic era
Verbatim from Sundar: “3.5 Flash is in a league of its own in the top right quadrant of intelligence vs. speed.” The argument is that agentic workflows are bound by latency × cost × parallelism, not peak benchmark Elo. The 93-subagent Antigravity demo at <$1,000 is the proof point. Anthropic’s argument is the inverse — Claude Sonnet/Opus on a single agent, slow and expensive, but better at the load-bearing step. Both arguments are coherent. The Flash bet is that swarms win.
3. The harness is the product
The Antigravity Harness, identified by name on stage, is now Google’s universal agent runtime. Spark uses it. Antigravity 2.0 uses it. The Managed Agents API exposes it. Sundar’s bug-fix demo uses it. Search agents will use it. One harness, multiple surfaces, exposed through one API. This is the most concentrated platform bet Google has made since GCP itself.
4. The runtime is now Google’s problem, not yours
The Managed Agents API is the line nobody has drawn this aggressively before. Quoting @Google: “In a single API call, you get the agent and a secure, hosted Linux environment — we handle the infrastructure so you can focus on the user experience.” That’s a category move. Anthropic doesn’t host runtimes. OpenAI’s agent runtime is sandboxed to its surfaces. Google now operates the Linux VM your agent lives in. The pricing implications are enormous and undocumented.
5. Search is becoming an agent surface, not a query surface
AI Mode at 1B MAU in one year. Antigravity-in-Search. Information agents. Agentic booking + agentic calling. The query box is becoming an agent surface, and the unit of search is shifting from “result” to “outcome.” This is the doctrine Sundar has been articulating for two years; I/O ‘26 is when it landed in the product as the default.
6. The vertical-integration story is the real moat
The chip (TPU 8t/8i) trains the model (Gemini 3.5) that runs in the IDE (Antigravity 2.0) that builds the app (Managed Agents) that runs on the cloud (GCP) that ships to the user (Gemini app, Search, eyewear, Workspace). No other AI lab owns all six layers. Apple has the device tier. Microsoft has the cloud tier. OpenAI has the model tier. Anthropic has the model tier. Google has all of them. Whether vertical integration translates into product wins is the question 2026 still hasn’t answered, but the keynote was the strongest argument yet that Google believes it will.
Where the doctrine diverges from the rest of the field
| Topic | Prevailing field position | Google’s I/O ‘26 doctrine |
|---|---|---|
| Frontier model strategy | ”Ship the biggest model, charge premium” (OpenAI, Anthropic) | Ship the fastest model, charge per-compute — Flash as the default surface |
| Agent runtime ownership | ”We make the model; you run the agent” (Anthropic, OpenAI before Agent Builder) | We make the model AND host the agent (Managed Agents API) |
| Multi-data-center training | ”One data center per training run” (Nvidia NVL72 baseline) | JAX + Pathways → 1M TPUs distributed across data centers as one cluster |
| AI media + provenance | ”Watermark TBD per vendor” | SynthID at 100B watermarked images — joint with OpenAI, ElevenLabs, Kakao on C2PA |
| Agentic commerce | ”Stripe’s MPP/UCP from the payments side” | Google’s AP2 + UCP from the demand side, paired with the 60B-product Shopping Graph |
| Wearable AI | ”Glasses are 12-18 months out” (Meta Ray-Ban Display, Apple Vision Pro 2) | Audio glasses ship fall 2026 with Samsung, Warby Parker, Gentle Monster — Android and iOS |
| IDE strategy | ”VSCode + AI sidebar” (Cursor, Windsurf, Copilot) | Standalone agent-first desktop app + CLI + SDK + Managed API |
The single biggest divergence from the field is the runtime ownership claim. Cursor doesn’t host. Claude doesn’t host. Replit hosts but only on Replit. Vercel hosts but only on Vercel. Google now hosts in the same call as the model. That’s the single most consequential platform difference for builders shipping into 2027.
The 12-month read — what builders should do with this
This is the actionable section. The keynote’s signal-to-noise is high for any of these positions:
| 🟢 If you’re … | What I/O ‘26 says to do |
|---|---|
| Building a coding agent | Move to Antigravity 2.0 + Managed Agents API. The harness is the same one Google uses internally. The Linux VM is hosted. The pricing edge case is the $100 Ultra tier — model the unit economics carefully. |
| Building agents on a competing stack | Wait two weeks then re-bench. The Managed Agents API is new; the harness’s edge cases will surface fast. Decide based on cost-per-completed-task, not benchmark Elo. |
| Shipping a Gemini-app-integrated product | Build Spark MCP integrations now. Canva, OpenTable, Instacart were the first three. The next 20 are the windowed land grab. |
| Running an SEO program | AI Mode at 1B MAU is the surface. Generative UI mini-apps are the new SERP. Build for AP2+UCP commerce. Your traffic story changes within 90 days. |
| Building a video-creation product | Test Gemini Omni Flash against Veo and Sora head-to-head. Omni’s iteration-on-your-own-video pattern is novel. SynthID watermarks are default. |
| Building consumer wearables | The audio-glasses partnership is open. Samsung, Warby Parker, Gentle Monster shipped first. The next wave of fashion houses and audio-OEMs onto Android XR is your land grab. |
| Operating a publisher | Plan for AI Mode + generative UI as the dominant referral surface. AP2+UCP will eat the bottom of your funnel for shopping queries. Diversify by Q4 2026. |
| Buying TPU vs. Nvidia | The Blackstone JV puts TPU rental into a new lane. Trainium is still the bear case per Gavin Baker. Watch the H2 2026 ramp curves — same advice he gave. |
| Choosing a model for new builds | Default to Gemini 3.5 Flash if your workload is agentic. Default to Claude/GPT for peak frontier tasks until 3.5 Pro ships next month. Re-evaluate then. |
| Shipping a Gemini-glasses experience | Apply for the Android XR partner program now. The fall 2026 launch window is the distribution event. Be on the shelf, not on the waitlist. |
🟢 The highest-value move for any builder in the room today: file for the Antigravity 2.0 + Managed Agents API early-access. The combination of the same harness Google uses + a hosted Linux runtime + Flash pricing is the most aggressive cost-per-agentic-task disclosure any major AI lab has put on the table this year. The $1,000-for-a-working-OS demo is the price floor Google is implicitly setting.
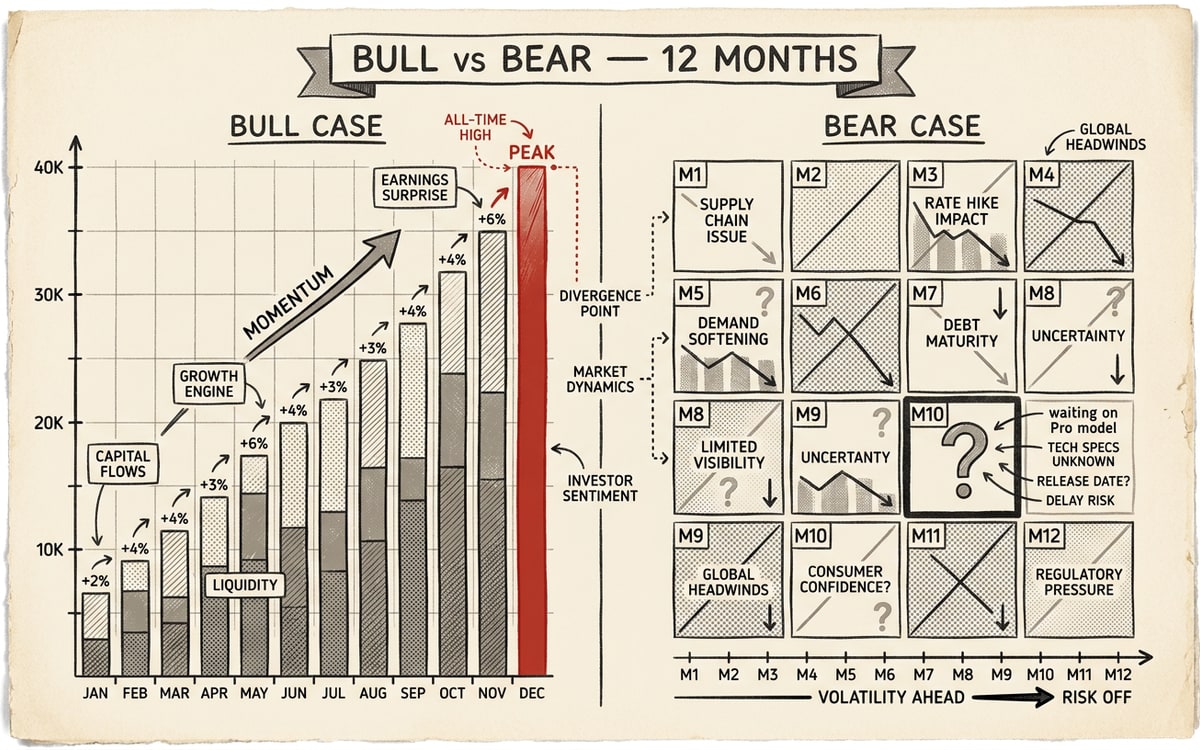
The bull case, the bear case, and the platform shift
Most read of I/O ‘26 will end on either “Google is back” (the bull case) or “Google is still chasing” (the bear case). Both are too simple.
🔴 The keynote does not change the model-leadership question. Until 3.5 Pro ships and benchmarks against Claude 4.5 / GPT-5.5, Google’s frontier-model claim has an asterisk. The asterisk was the most-discussed thing on X today. @tenobrus, @RudyReaper, @apoorvjain25, @ammohitchaprana all caught it. They were correct.
🟢 The keynote does change the platform question. Antigravity 2.0 + Managed Agents API + TPU 8t/8i + Pathways multi-data-center training + Search-as-agent + AP2/UCP commerce is the single largest integrated platform release any AI lab has shipped on a single day. Nobody else has all the layers. The question shifts from “who has the smartest model?” to “who has the platform on which models compound?” On that question, Google now has the strongest argument it has had since the original 2017 Transformer paper.
🟡 The keynote does not change the consumer-trust question. The “feature slop disguised as innovation” critique from @GageOnX is correct as critique — AI is now in the Search box, the Maps box, the Docs box, the Keep box, the Gmail box, the YouTube box, and the Photos box. The cost of all this AI being in every surface is the user’s surplus attention. Google now has to prove that Spark is a daily-use product, not a daily-distraction product. The Daily Brief is the first test. Watch retention at the 30-day mark.
🟢 What we’d watch for the next 12 months:
- Gemini 3.5 Pro ship + benchmark. Mid-June. The single largest determinant of whether the bull case compounds or the bear case calcifies.
- Antigravity 2.0 community. GitHub repos using the Managed Agents API. The first viral OSS Antigravity-built project. If a developer ships something Cursor-shaped on Antigravity, the moat is real.
- TPU 8t/8i ramp curves. H2 2026 — Gavin Baker’s prediction. Watch the AWS Trainium 3 launch in parallel.
- Spark retention at 30 days. Google AI Ultra subscribers in the US first. If retention is below 40%, the agentic-assistant thesis is wrong. If it’s above 70%, Google is replicating the GPT-5 ChatGPT-paid retention curve.
- The Blackstone JV operationalization. 500MW online in 2027 is the headline. The first tenant outside Anthropic is the read-through.
- The publishing ecosystem response to AI Mode + generative UI. Lawsuits, opt-outs, and the Search Console “AI Mode” reporting will surface within 60 days.
- AP2 + UCP merchant adoption. Stripe vs. Google standards war for agentic commerce. If Shopify, Amazon, or Walmart picks a side, the protocol war ends fast. If they all sit out, the war drags.
- The Android XR glasses fall launch. First-week sell-through is the signal. Audio-glasses + Gemini API + cross-platform iOS support is the most credible non-AirPods consumer-AI hardware bet of 2026.
The single sentence I’d write under the keynote tape is this: Google shipped a wide, opinionated platform on May 19, 2026 — wider than anyone else’s platform, deeper than anyone else’s distribution, and with one giant question mark (the Pro model) that resolves in three weeks. If the Pro ships and benchmarks are competitive, the bull case prints. If not, the bear case calcifies, and we get to write the follow-up.
Either way, today was not a normal I/O. The 3.2-quadrillion-tokens-a-month curve is the company now. The Antigravity harness is the platform. The TPU 8t/8i + Pathways stack is the moat. The Search box becoming an agent is the consumer story. Android XR is the next surface.
And the missing Pro is the asterisk that owns the conversation until June.
We’ll be writing the June follow-up.