At 15:41 UTC on May 19, 2026, Eli Mernit, co-founder and CEO of Beam (the Y Combinator W22 company that shipped the open-source beta9 serverless GPU runtime), posted the launch tweet for Capsule.
Introducing Capsule — The Infra Framework for AI Apps
Capsule is a Python framework that provides infrastructure primitives for sandboxes, auth, session management, integrations, and payments.
Capsule is @supabase for AI apps. You get a powerful Python SDK to iterate fast, and…
— @mernit May 19, 2026
The framing is sharp. The product, after a wheel extraction and a four-hour read of the source the docs don’t show you, is real but not what the tweet claims it is. This essay is the audit.
Capsule is a closed PaaS with three OSS skins
The 280-character launch tweet describes a “Python framework that provides infrastructure primitives.” The repo audit found something more specific. Capsule is not a single open-source GitHub repo. It is a hosted, mostly closed-source platform-as-a-service by Beam, with three thin OSS-friendly skins:
| Public artifact | What it contains | License |
|---|---|---|
beam-cloud/capsule-docs | Mintlify docs site source (.mdx files) | MIT |
beam-cloud/capsule-examples | 9 starter app templates referenced by capsule create | none |
beam-cloud/capsule-computer-example | A larger demo app (“agent with a computer”) | none |
pip install cpsl (PyPI) | The actual SDK + capsule CLI — shipped as a wheel only, no source repo | no LICENSE in the wheel |
capsule.new | Marketing site (React SPA, no GitHub link surfaced) | n/a |
docs.capsule.new | Mintlify-hosted docs | n/a |
The Python package on PyPI is named cpsl, version 0.3.161 at clone time — the version number alone suggests at least 160 internal release cuts during development, which is a useful signal about how long Beam has been quietly building this. The wheel is 159 KB. Extracted, it contains roughly 16,400 lines of Python plus a 1,592-line auto-generated betterproto gRPC stub file at clients/capsule/__init__.py.
The gRPC stubs are the most important finding. They prove Capsule’s backend is a closed gRPC service. The SDK is a client. The gateway is hardcoded:
GATEWAY_HOST = "gateway.capsule.new:443"You cannot self-host this. There is no offline mode. capsule serve app.py:app, which the quickstart presents as “local hot-reload,” is in fact a bidi-streaming gRPC RPC (ServeStream) that uploads your source to Beam’s gateway and runs a hosted dev runtime that streams hot-reload events back to your terminal. The docs are careful with their wording. They never claim Capsule is self-hostable.
Capsule is a framework and hosted runtime for shipping AI apps with chat, pages, state, integrations, tasks, and auth.
— Capsule docs, index.mdx
Three repos created in late April 2026 in preparation for the May 19 launch. One committer across all of them: Luke Lombardi, Beam’s CTO, Mernit’s college roommate from Binghamton. Zero stars from the community at clone time. One star on capsule-examples (likely an employee). The docs repo, MIT-licensed, has 18 commits over 4 weeks. The examples repo, unlicensed, has 23. That is the entire public surface area.
The five primitives, scored against the code
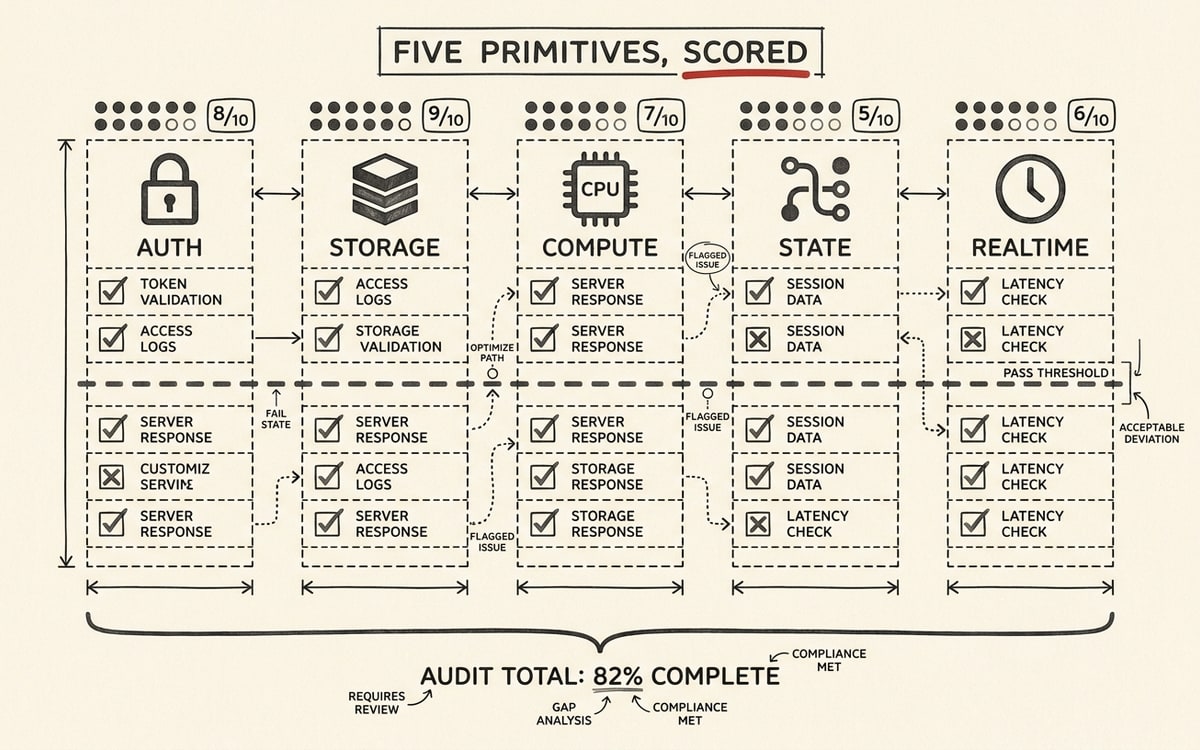
The tweet enumerates five primitives. The repo audit walked the source for each, traced the public class names, and scored 0–3 on shipped-ness, not promised-ness:
| Tweet primitive | Implementing module | Score | One-line verdict |
|---|---|---|---|
| Sandboxes | cpsl/image.py + Beam’s beta9 runtime | 🟡 2/3 | Container-per-app-user, not an E2B-style sandbox.run_code() |
| Auth | cpsl/session.py:UserInfo + gRPC RequestLogin/ConfirmLogin | 🟡 2/3 | Real, hosted, opaque — no BYO IdP |
| Session management | cpsl/session.py:927–1900 | 🟢 3/3 | The strongest part of the SDK, ~1000 LOC |
| Integrations | cpsl/integration.py + cpsl/pipedream.py | 🟢 3/3 | 10 OAuth providers + Pipedream proxy |
| Payments | App(price=, pricing_type=) + CreateCheckout RPC | 🟡 2/3 | Two-field API, Stripe Connect, 10% platform fee |
The pattern is sharp. Where Capsule actually composes well (sessions, integrations), the surface is wider and better-designed than equivalent layers in LangChain or LiteLLM. Where the tweet implies a discrete primitive (sandboxes, payments), the SDK is thinner than the word “primitive” suggests.
1. Sandboxes — the word does more work than the code
The framing implies a per-call, isolated, language-aware code-execution primitive — the E2B or Modal Sandbox shape. The code doesn’t ship that. Capsule’s “sandbox” is the runtime container that hosts your entire app, one per app-user, provisioned by Beam’s beta9 GPU container runtime under the hood. The declaration site is cpsl/image.py:
import cpsl
app = cpsl.App( name="my-app", image=cpsl.Image(python_packages=["baml-py==0.220.0", "pydantic>=2.13.2"]), cpu=0.25, memory=512, keep_warm_seconds=120,)That is the entire sandbox surface in the SDK. No sandbox.run_code(...). No sandbox.open() / sandbox.close(). The closest analogue is session.terminal("name") (cpsl/session.py:672–870), a streamed shell that lives inside the same app runtime, not a fresh isolated jail. If you wanted to use Capsule the way the agent-tooling world uses E2B (let an LLM run arbitrary Python in an isolated process and stream stdout back) you cannot. The capsule-computer-example repo demonstrates the workaround: a process=True task plus a mounted /computer/users/<user> filesystem to give each end-user a working directory. That’s a convention, not a primitive.
The tweet’s word sandboxes is doing two jobs. It markets to the agent-tooling crowd familiar with E2B. It also accurately describes what Capsule does for deployed apps: each end-user of your app gets their own runtime container. Both are true; only one matches what most developers will hear.
2. Sessions — the strongest layer in the SDK
The Session class is the largest single class in cpsl/session.py, spanning roughly lines 927 through 1900. Its public surface is genuinely well thought through:
@app.message()async def handle(session: cpsl.Session, msg: cpsl.Message): intent = await b.ClassifyMessage(message=msg.text)
# Scoped KV — survives across handlers last_query = await session.get("last_query", scope="user") await session.put("last_query", msg.text, scope="user")
# Streaming reply from any model SDK / BAML async with session.stream_reply() as reply: async for chunk in answer_stream(intent): await reply.append(chunk)
# Show a task progress block in the chat await session.show_task(await long_running.submit())
# Blocking prompt — require an integration before continuing creds = await session.require_integration(cpsl.GITHUB, reason="to clone repo")The scopes are the part that matters. scope="session" | "user" | "owner" | "app" runs through the entire data layer — sessions, collections, KV. UserInfo.owner_id (cpsl/session.py:365–373) returns org:<id> for org members or the user id otherwise. The framework is opinionated about multi-tenant scoping in a way that LangChain has never been. For a builder shipping a paid B2B agent product, this is the kind of opinionation that compresses weeks of plumbing into a declaration.
A reply in the launch thread, @LeoTava8, caught this exact dimension:
The “same 5-7 infra primitives” observation is the key line here. Every AI app team independently builds sandboxes, auth, and session management because the model is just a dependency — the infrastructure around it is the actual product. Smart to extract and standardize what everyone rebuilds.
— @LeoTava8 May 19, 2026
The criticism the audit can level here is not the design — it is the closed-ness. The Session abstraction is good. You cannot extend it, fork it, or run it without gateway.capsule.new:443 in the loop.
3. Integrations — the place the framework is most genuinely ahead
The integration layer ships with a real list of OAuth-wired providers built in (Google, Gmail, Calendar, Drive, GitHub, Linear, Outlook, Tailscale, AWS) plus a Pipedream proxy that opens up the long tail. The unified decorator pattern is the point:
# cpsl/integration.py — first-class providersapp = cpsl.App( name="research-agent", integrations=[ cpsl.GITHUB, cpsl.LINEAR, cpsl.GoogleDrive(scopes=["readonly"]), cpsl.Pipedream(app_slug="slack"), # 1000+ apps via Pipedream ],)
@app.message()async def handle(session, msg): gh = session.integrations["github"] # OAuth credentials, already refreshed linear = session.integrations["linear"] # ...This is one of the cleanest integration surfaces shipped this year. CrewAI doesn’t have it. LangChain has it spread across langchain-community packages that are non-uniformly maintained. Mastra has its own version but it’s TypeScript-first. For a Python builder, this single layer is probably the strongest argument for adopting Capsule — and it composes naturally with the session layer (the require_integration blocking prompt forces an end-user OAuth flow inside the chat).
4. Payments — two fields wide, ten percent deep
The entire payments surface, in the SDK, is two fields on App(...) and one RPC:
app = cpsl.App( name="research-agent", price=1500, # price in cents pricing_type="monthly", # or "one_time")Behind those two fields, CapsuleService.CreateCheckout wires up Stripe Checkout and Stripe Connect. Beam handles the merchant-of-record plumbing. Customers pay through Capsule. Builders get a payout. And, per the docs:
Capsule takes a 10% platform fee on app sales.
— Capsule docs, features/pricing-and-payments.mdx
This is the most aggressive monetization stance in the comparable framework set. Supabase doesn’t take a cut of customer revenue. Mastra doesn’t. LangChain doesn’t. Inngest doesn’t. Vercel takes infrastructure fees, not transaction percentages. Beam is running a Heroku-plus-Stripe-Connect-plus-a-take-rate model — and the take-rate is the load-bearing piece.
The 10% number lands differently at different price points. On a $20/month Capsule app, it’s $2 — invisible. On a $5,000/month enterprise agent agency built on top of Capsule (the Greg Isenberg agency playbook shape), it’s $500/month, recurring. For an indie builder testing pricing, that’s friction in the wrong direction. For a serious B2B builder hitting Capsule’s monetization story when scoping, it is the first reason to write the same code on Modal or Beam’s own beta9 directly and run Stripe themselves.
The launch thread surfaced no comment on the 10%. Five hours in, @AIwithArsalan was the only independent voice praising the framework substantively (“The strongest part of Capsule might just be how much repeated infra work it removes”) and no reply, anywhere in the visible thread, raised pricing. This is a real risk for Beam’s positioning — the developer audience the launch reached is mostly indie builders who haven’t yet hit a customer paying $5K/month through Stripe Connect. The pricing critique is coming. It’s just lagged by the size of the largest customer not yet hit.
What the tweet didn’t say — the other six concepts
The five tweet primitives obscure that the docs index page lists eight first-class concepts, not five. The three the tweet omits are the ones likely to be more important in practice:
Collections — Mongo-flavored scoped tables
cpsl/db.py (1,126 LOC) implements typed document storage with the same scope system as sessions:
memories = app.collection( "memories", columns=["topic", "note", "source"], scope="owner", # auto-filtered by org/user inside handlers sortable=True, filterable=True,)
await memories.insert_one({"topic": "company note", "note": "...", "source": "chat"})notes = await memories.find({"topic": "company note"})This is the line in the audit that the Supabase analogy breaks hardest on. Supabase’s Collections layer is literally Postgres — with full SQL, relational joins, foreign keys, row-level security, vector embeddings. Capsule’s Collections are Mongo-flavored, scope-tagged, document-shaped. The choice was deliberate (LLM-generated objects are document-shaped) and it composes well with the rest of the SDK, but to call it Supabase-equivalent is to obscure a category difference.
Pages — the React-bundling DSL
cpsl/ui.py (1,334 LOC, plus page_bundle.py) ships a DSL widget tree that compiles to React:
@app.page("Knowledge", icon="files")def knowledge_page(): return cpsl.ui.Page([ cpsl.ui.Text("Workplace knowledge", style="heading"), cpsl.ui.Table(collection=memories, columns=["topic", "note", "source"]), cpsl.ui.ActionCard(title="Add memory", action=add_memory), ])For shipping operator UIs, this is the part of Capsule that is most likely to feel novel to developers coming from LangChain / CrewAI. None of the comparable Python agent frameworks have a built-in UI layer. They expect you to bring Streamlit, Gradio, or a separate Next.js app. Capsule’s Pages is the closest the Python-AI stack has come to “Retool, but in-app and code-defined.”
Tasks, schedules, channels, filesystems, workflows
Briefly: tasks (@app.task(retries=, timeout=, lock=, process=True)) have real distributed locks and subprocess isolation. Schedules use cron syntax. Channels (Telegram, Slack, WhatsApp, API) plug into the same @app.message() handler. Filesystems are backed by Beam’s own Airstore product, with an MCP tool registration path. Workflows are the smallest of the six (192 LOC) — named, session-backed multi-step flows triggered from a sidebar.
All five are substantive (3/3 on the audit’s shipped-ness scale), all five compose into the same App(...) declaration, and none of them were in the launch tweet.
The audit’s most useful finding: the day-1 surface is enormous
Beam shipped eight first-class concepts simultaneously: sessions, integrations, collections, pages, tasks/schedules, channels, filesystems, workflows. The breadth is unusual for a launch. Supabase, by contrast, grew its surface outward from Postgres+auth over four years — adding storage in 2021, edge functions in 2022, realtime in 2022, vector in 2023, queues in 2024. The wedge was always Postgres. The rest came after.
Capsule’s day-1 bet is the opposite: ship the full stack at once, opinionated, closed. Each layer is real. None is battle-tested. The risk is the breadth-versus-depth one — a framework that does eight things well at v0.3 will get cut on the one axis it does worst the moment a serious customer hits production. The session layer is the best of the eight; the sandboxes-as-app-runtimes positioning is the most likely to bite.
The Supabase analogy — does it survive the wheel extraction?
It doesn’t.
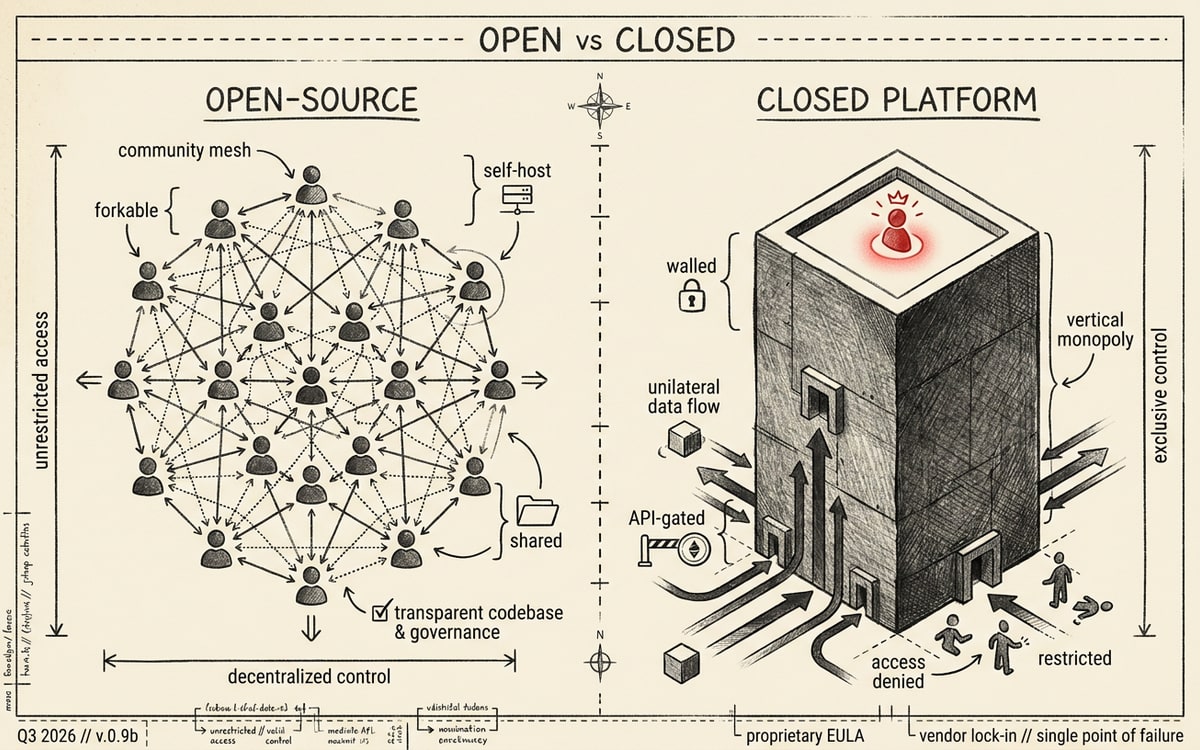
The Supabase analogy is doing two jobs in Mernit’s tweet. Job one: claim a category position. Supabase is the open BaaS reference. AI infrastructure has none. Whoever gets to be “Supabase for AI” gets a category seat. Job two: trigger a specific developer recognition — “oh, it’s the URL-and-keys experience, but for agents.” The first job is marketing. The second is honest if and only if Capsule’s openness profile rhymes with Supabase’s.
It doesn’t.
| Axis | Supabase (Apache-2.0) | Capsule |
|---|---|---|
| Server code license | Apache-2.0, full source | No LICENSE in the wheel; gateway closed |
| Self-host path | Documented, supported, used by many | None. gateway.capsule.new:443 hardcoded |
| Primary DB | Postgres, full SQL, full extensions | Mongo-flavored scoped Collections |
| GitHub stars (main repo) | ~70,000 on supabase/supabase | 1 across all 3 capsule-* repos |
| Distinct committers | 200+ | 1 (Luke Lombardi, CTO) |
| Take rate on customer revenue | 0% | 10% via Stripe Connect |
| Funding raised | $80M Series B at $2B (2024) | $3.5M seed (May 2022), no round since |
The shape rhymes — both are BaaS, both let you ship faster, both have opinionated SDKs. The substance doesn’t. A more honest framing is “Vercel/Heroku 2.0 for Python AI apps, with a rev share.”
That’s still a real and interesting product. Beam doesn’t need the Supabase comparison to be true to have built something. They need the Supabase comparison to be true to claim the category seat. The audit finds: product shipped, framing oversold.
@Karmedge, a YC S24 founder, asked the load-bearing question 21 minutes after the launch:
interesting is it a drop in replacement for supabase?
— @Karmedge May 19, 2026
At T+5 hours into the launch window, the question had zero replies from Mernit or from anyone at Beam. The silence is the answer.
The founder and the funding shape
Eli Mernit is Beam’s CEO and co-founder, with Luke Lombardi (CTO). They were college roommates at Binghamton. Mernit’s career arc, in his own LinkedIn order: 2015–2017 “Digital Nomad” working under what eventually became the Smartshare, Inc. legal entity; 2017–2019 Technical PM at BlockApps (enterprise blockchain); 2019–2020 Technical PM at Hydrogen (fintech APIs); 2020–2021 at the New York Times; founded Slai in June 2021, rebranded to Beam between 2022 and 2023, Y Combinator W22.
The funding history is a single seed round. $3,500,000 in May 2022, led by Tiger Global, with YC, Charge Ventures, Uncorrelated Ventures, Twenty Two Ventures, Soma Capital participating, plus angels Guy Podjarny (Snyk founder) and Jason Warner (ex-GitHub CTO, now CEO of Poolside). Per TechCrunch, the round closed under the Slai brand. Crunchbase confirms one funding round total. No publicly disclosed round since the 2022 seed.
Latka claims ~$1M ARR by end of 2024. That number is uncorroborated and conservative-looking on a YC-backed company with named enterprise customers (Coca-Cola, Magellan AI, Geospy, Stratum, Shippabo, Hooktheory, Gepetto, Ogilvy, Frase, Jamie, EdgeImpulse) on their flagship beta9 product. The team is 5 employees per YC’s company page (May 2026), 7 per Latka (December 2024).
The shape this draws: a small, technically deep team, on a single seed round from four years ago, currently bridging on revenue, launching their second product on top of their first. Capsule isn’t a greenfield bet — it’s the application layer above beta9, which has been shipping since 2024. The infra risk is genuinely low. The commercial risk is concentrated in whether Capsule can capture enough developers fast enough that the 10% take-rate compounds before AWS Bedrock AgentCore, Cloudflare Agents, or OpenAI’s Agent Builder commoditize the bundle.
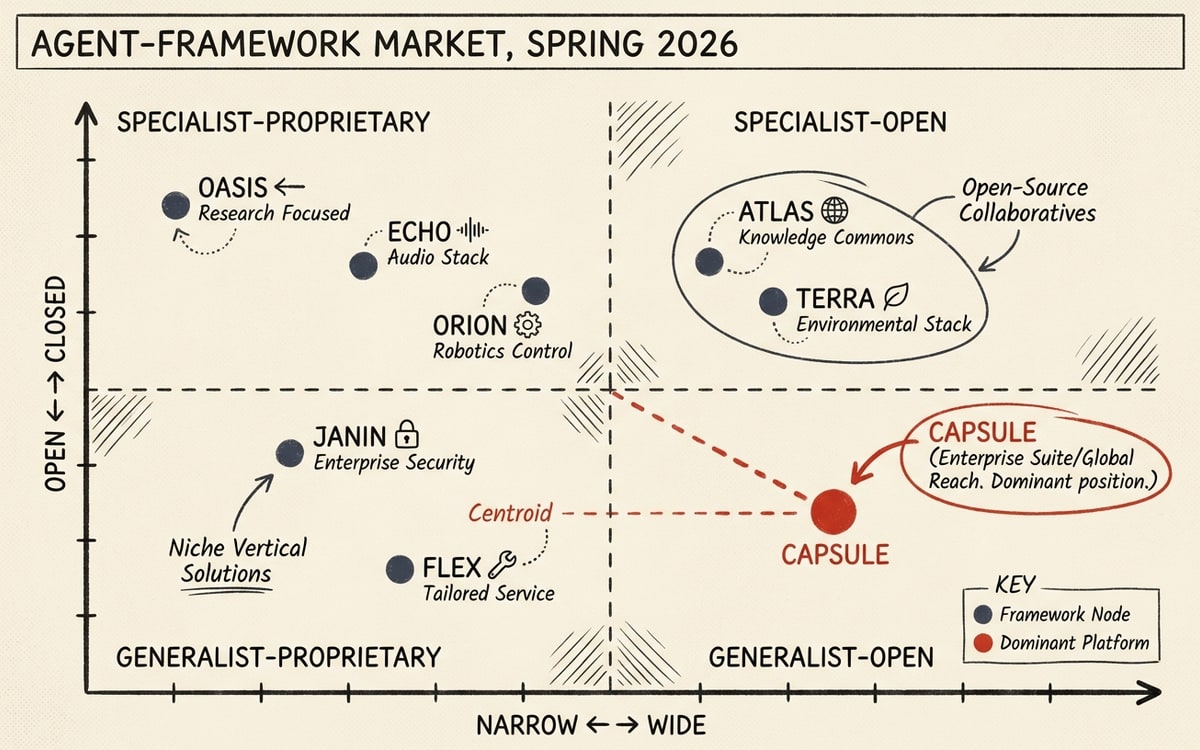
The competitive set is louder than the launch thread suggests
Capsule lands in a category that shipped multiple credible competitors in the last 60 days. Read in date order:
- Mastra (YC W25) — TypeScript-first agent framework, open-source, 8 employees, founded 2024 by ex-Gatsby devs. Took the same category seat 6 months earlier in the JS ecosystem.
- Cloudflare Agents — launched during Agents Week 2026 in April, runs on Workers + Durable Objects, per-user isolated runtime baked into the edge network. Distribution moat that Capsule cannot match.
- AWS Bedrock AgentCore — announced at re:Invent 2025 in December, with a policy update in December 2025 clarifying enterprise positioning. AWS has the enterprise sales motion that no startup has.
- OpenAI Agent Builder — DevDay 2025 launch, opinionated agent shell that ships with OpenAI’s model defaults.
- Letta (formerly MemGPT), CrewAI, LangGraph Cloud, Inngest Agent Kit, Vercel AI SDK — each owning a narrower slice.
Capsule’s slot in this map is the broadest bundle, Python-only, closed-source. The breadth is the differentiation. The closed-source is the risk. Mastra, the most directly comparable startup, is open-source, $4M seed, YC W25. They picked the inverse strategy: openness as moat, narrower vertical. Two more quarters will tell us which posture compounds faster.
What the launch thread itself proves
The data point we can pull most cleanly from the launch is the discourse. The tweet’s engagement at T+5 hours: 22,109 views, 77 likes, 14 reposts, 26 replies, 3 quote-tweets, 47 bookmarks.
Mernit’s median tweet does not pull these numbers — his February 2026 essay Your Company is a Filesystem hit 1.8 million views and 3,346 likes. The Capsule launch is ~1.2% of that essay’s reach. Three readings:
🟡 The launch was under-promoted. No coordinated thread, no cross-post from Beam’s company handle in the first hours, no obvious VC amplification. The tweet stands alone.
🟡 Mernit’s audience is curated for thought-essays, not product launches. The follower-to-engagement ratio shifts hard when the post asks for action instead of agreement.
🔴 The audience that actually engaged is mostly indie builders. Of the 18 substantive replies the xAI Agent Tools API pulled, none are from notable VCs (Tiger, a16z, Sequoia, Founders Fund), none from YC partners (Garry Tan, Michael Seibel, Dalton Caldwell, Tom Blomfield, Aaron Epstein), and none from competing framework founders (Mastra, LangChain, Inngest, Letta). One reply from @palashshah, a LangChain engineer, said only “congratulations Eli!” — the closest the discourse comes to competitive notice. He didn’t engage on substance.
The thread’s most insightful reply, the one that frames the strongest bullish argument for Capsule, came from @rohanpaul_ai:
Just in time, the agent era so needs its own backend defaults. imo, agentic software is entering the same phase web apps entered around 2013-14, when people stopped proving they could assemble plumbing and started proving they could create value on top of it.
— @rohanpaul_ai May 19, 2026
That’s the bull case. If 2026 is the 2013 of agents (the year people stop building plumbing and start building on top of standard plumbing) then category-leading frameworks are the ones that ship the most opinionated bundles. Capsule has the most opinionated bundle in the comparable set. That is a real argument.
The bear case is colder. Closed-source frameworks in developer infrastructure have a structurally harder time bootstrapping community. Supabase, Inngest, Mastra, Triplit, Convex are all open-core. Heroku tried closed-and-opinionated and got eaten by Vercel and Render. The 10% take-rate compounds the same way it compounded against Heroku once AWS Lambda existed. Capsule needs to land enterprise customers fast, before the developer audience routes around it.
What I’d watch over the next 90 days
🟢 Will any high-signal voice break the silence? Five hours of zero VC/YC-partner engagement is not unusual for a soft launch. Five days would be a signal. The bar to watch is one substantive quote-tweet from someone with editorial gravity (Tom Blomfield, Garry Tan, Pat Grady) in the next two weeks.
🟢 Will Beam open-source the SDK? The closed-source posture is the single biggest reason Capsule’s category position is contested. A LICENSE file on cpsl between now and Q3 would change the bear case materially. Mernit hasn’t signaled either way.
🟢 Will the 10% become a wedge issue? The pricing critique is lagged. It will arrive the moment a builder hits Stripe Connect for the first time and realizes Beam is collecting on outcomes Beam didn’t sell. Watch for the first thread that articulates this.
🟡 Will the Pages DSL pick up community examples? The Pages layer is the single most novel piece of Capsule and the one most likely to generate viral examples. If it does, the framework’s distribution problem starts to solve itself.
🔴 The Cloudflare Agents and AWS AgentCore distribution overhang. Capsule is racing both. The window to establish category leadership in the Python AI app layer is probably the next two quarters. If Cloudflare’s Agents Week 2026 launches a Python SDK with comparable surface area in Q3, Capsule’s strongest argument (“the only opinionated Python bundle”) gets contested in months instead of years.
What the audit found, in one paragraph
Capsule is a real, well-engineered Python application platform with an unusually polished day-1 surface. The session layer is the best in the category. The integration surface is one of the cleanest in the Python AI stack. The eight first-class concepts compose into a single App(...) declaration that is easier to read than equivalents in LangChain or LangGraph. Beam shipped something good. They also pitched it as the open-Postgres analog when it ships closed, hardcoded to one gateway, with a 10% take on customer revenue. The pitch was sharp. The product is real. The Supabase comparison doesn’t survive a wheel extraction.
What happens next is whether the comparison was a launch-day rhetoric or a real positioning bet. If the SDK gets a LICENSE and the gateway becomes optional, the framing repairs itself. If neither happens, the next 90 days will produce the first serious critique thread — and Capsule will get to argue what it actually is, on the merits.
Either outcome makes for a better read than the launch tweet itself.