The closing fireside at Stripe Sessions 2026 was packaged as a fun closer. Two well-known investors across from the Collison brothers, an audience that had already sat through 288 product launches the day before, the framing of “Day 120 of the singularity” — a Patrick Collison line that became the meme of the conference (@kognise7).
But this was the most operationally specific talk on the playlist, and the substance was buried under jokes about eBay, hydration agents, and Iron Man cosplay. Two men who, as of this week, are the most senior outside hires inside Meta Superintelligence Labs sat on a public stage and lightly disclosed three things that hadn’t been on the record before: who actually owns Meta’s compute strategy, what Meta is building internally to allocate token spend across thousands of engineers, and what was wrong with the data pipeline at MSL when they walked in.
The dossier from the August 2025 reorg coverage was already public. Bloomberg reported the four-pillar split into TBD Lab, FAIR, AI Products, and MSL Infra. Wired confirmed the early defections. The Verge traced the hiring math. Business Insider printed the Wang memo. On 12 January 2026, Zuckerberg posted on Threads that “Meta Compute” was a new top-level initiative led by Santosh Janardhan and Daniel Gross.
What hadn’t happened until this week was Gross or Friedman speaking publicly, in the first person, about how MSL actually runs.
What was already known vs what just got disclosed
| Topic | Pre-Sessions baseline | Disclosed at Sessions 2026 |
|---|---|---|
| Daniel Gross’s role at Meta | Public reporting paired him with Janardhan as co-lead of “Meta Compute” (Reuters, 12 Jan) | First time he framed it himself: “one of the things I’m responsible for today is Meta’s compute strategy, where Nat and I both work” — singular, no co-leads named |
| Nat Friedman’s role | The Information’s org chart listed him with 6 direct reports under MSL Products | Confirmed on stage as the operator running culture/tooling change inside MSL — “we’re definitely doing it right now at Meta. We ship.” |
| Token-budgeting at Meta | No prior reporting | Meta is building an internal “FinOps for tokens”: every IC gets a token budget, LLMs grade the economic value of generated tokens, ICs are framed as “portfolio managers in a hedge fund” |
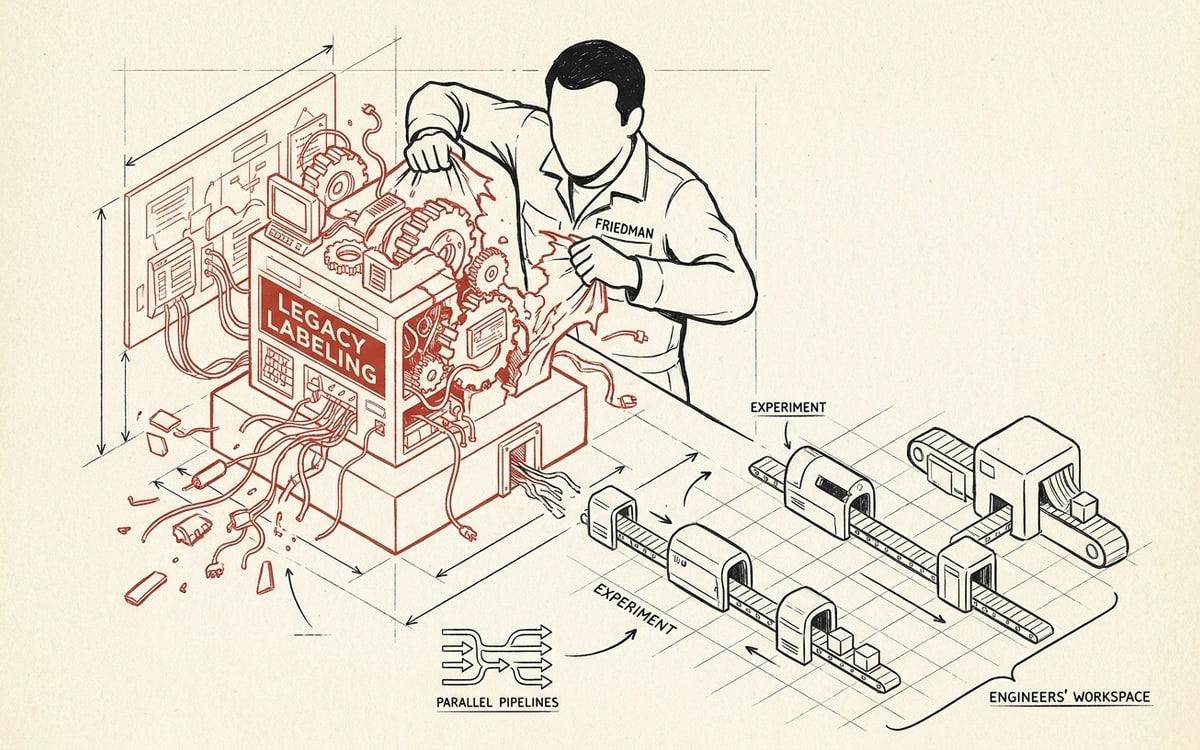
| MSL data-labeling pipeline | Times of India (Oct 2025) reported Friedman told staff to “use the AI tools of GitHub and Vercel as Meta’s tools are worse” | Specific anecdote: Friedman ripped out a legacy labeling tool because approval gates were forcing engineers to bundle tasks and run them less often |
| Aggregate AI capex framing | Wall Street consensus pinned 2026 hyperscaler capex at $600–725B (MUFG, Reuters, Om Malik) | Gross reframed it: “global GDP would be just under 1%” and “we’re going to be north of 2% of US GDP on AI capex” |
| Mission alignment with Zuck | Zuck’s Personal Superintelligence note (July 2025) was the public framing | Both speakers used “we” without hedging. Zero daylight visible between MSL leadership and Zuckerberg’s framing on stage. |
| Yann LeCun | LeCun left in November 2025 and went scorched earth on Meta in interviews | Not named once. The implicit framing — “the prime project at every AI lab is to remove humans from the loop and get to self-improvement” — is the bet LeCun explicitly rejects |
The compute disclosure that wasn’t supposed to be a disclosure
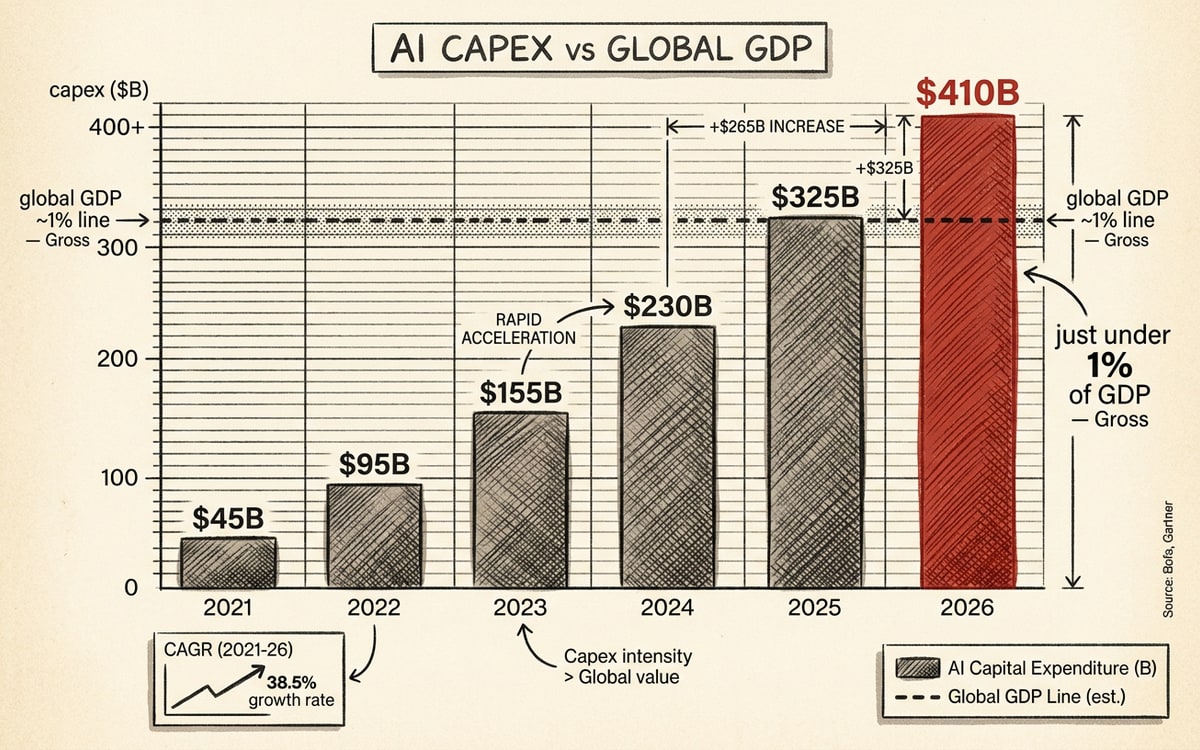
John Collison set up a softball: what’s the latest figure for aggregate compute capex as a fraction of global GDP?
Gross answered without breaking stride.
“Global GDP would be just under 1%. So, there’s a lot happening … we’re spending right now as a country — earlier I gave you the global number — but as a country we’re, I think, going to be north of 2% of US GDP on AI capex.”
— Daniel Gross, on stage at Stripe Sessions 2026
The 1% figure is the upper end of consensus. MUFG’s December 2025 chart pack pegged big-five hyperscaler 2026 capex at $602B, ~75% AI-specific. By Sessions week the running tally had crossed $700B for the four largest US hyperscalers alone after Meta lifted 2026 guidance to $125–145B, Microsoft and Alphabet held their growth trajectories (Reuters), and Om Malik’s post-earnings tally put the four-firm number “near $700 billion.” Add neoclouds, sovereign capex, and startup-direct GPU procurement and Gross’s “just under 1% of global GDP” (roughly $1.1T against a ~$115T base) is plausible.
The “north of 2% of US GDP” framing is more aggressive. US GDP is on track for ~$30T in 2026; 2% is $600B. Wall Street consensus pre-Sessions was $400–550B. Gross is quietly forecasting higher than the analyst aggregate, presumably because he is sitting on Meta’s internal numbers (@vic_crane noted Meta alone raised guidance by $107B in a single cycle).
The X discourse around the Q1 2026 earnings cycle reads as a market that has stopped reflexively rewarding the spend. Meta’s stock dropped 6% after-hours when guidance went up. The mood:
Imagine asking Mark Zuckerberg “how do you know these investments are sufficiently positive ROIC?” When bro just explained to you he’s building personal superintelligence.
— @taobanker Apr 30, 2026
Zuck himself, on the call:
We’re on track to deliver personal superintelligence to billions of people.
— Mark Zuckerberg, via @TheTranscript_, Apr 30, 2026
That is the framing under which Gross is now responsible for the largest infrastructure budget any technology company has ever committed to.
AI capex by hyperscaler — 2025 vs 2026
| Company | 2025 capex (actual) | 2026 capex (guidance, end-Apr) | Delta | Source |
|---|---|---|---|---|
| Microsoft | ~$88B | ~$160B+ (“growth trajectory through FY27”) | +82% | Reuters |
| Alphabet | ~$75B | $175–185B | +145% | Reuters |
| Amazon | ~$120B | $200B (held) | +67% | Om Malik |
| Meta | ~$72B | $125–145B (raised from $115–135B) | +93% | Yahoo Finance |
| Big Four total | ~$355B | ~$700B | +97% | Reuters |
| As % global GDP (~$115T) | ~0.31% | ~0.61% | — | derived |
| As % US GDP (~$30T) | ~1.18% | ~2.33% | — | derived |
That last row is the load-bearing one for Gross’s “north of 2% of US GDP” claim. He hits the threshold with the four hyperscalers alone, before counting xAI, Oracle (which has guided its own multi-tens-of-billions OCI buildout), CoreWeave, Lambda, the sovereign-cloud commitments out of UAE/Saudi/Korea, and the Tempo-style next-gen settlement infrastructure (Stripe Sessions Part 1) that runs on its own GPU pools.
The labeling tool that was structurally wrong
The most operationally specific disclosure of the talk wasn’t about money. It was about a single internal tool.
“At Meta, one of the things that we’ve done in the first few months is change what tools people are using because tools drive culture a lot. … We had a tool that we used for collecting labels for training AI models. That tool was extremely cumbersome and had lots of approvals. As a result, it was very expensive to fire up a new labeling task. People would design their labeling tasks differently — they would bundle all kinds of tasks into a single task and run it less often.”
— Nat Friedman
Read that paragraph carefully. The bottleneck inside MSL (the highest-profile AI lab in the world, with Alexandr Wang running it, with $145B in 2026 compute behind it) was the activation energy of starting a new labeling experiment.
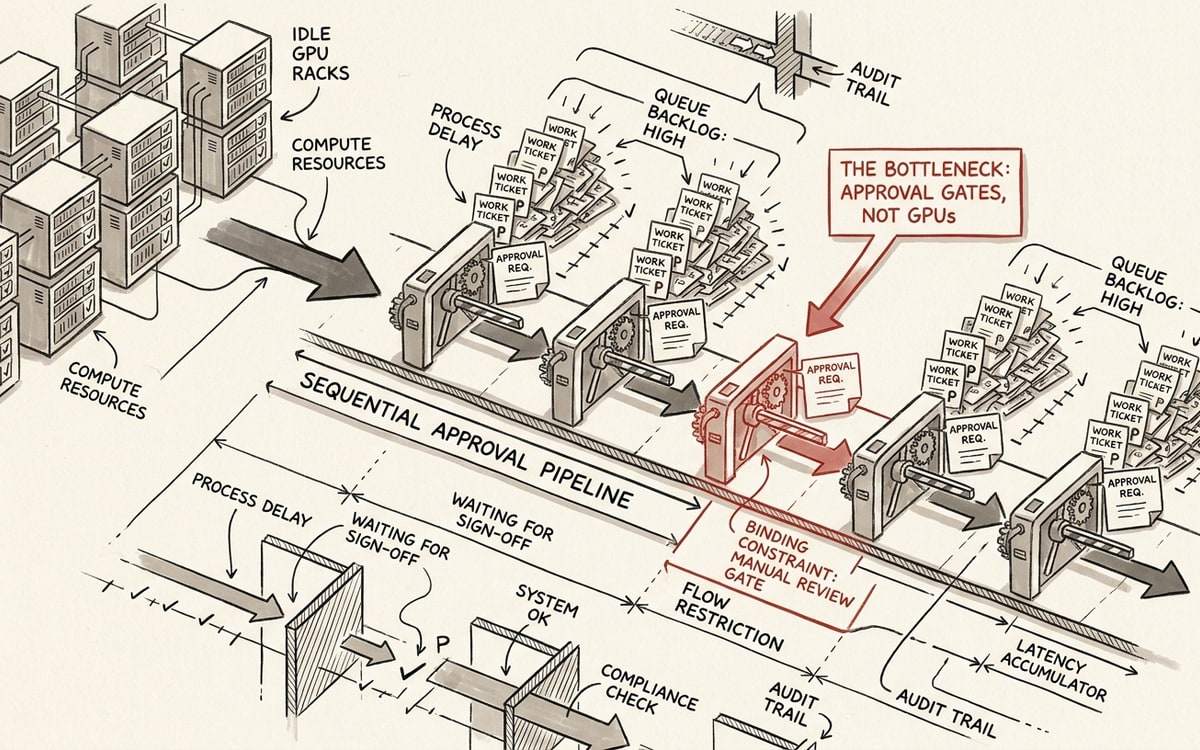
This is the inverse of the talent-war story. The Wired and Verge reporting from August 2025 framed MSL’s problem as people: who’d been hired for $200M+ packages, who left after a month, who refused to leave OpenAI (Wired, The Verge). Friedman’s disclosure says the people are fine. The constraint was permission slips. The revealed preference of researchers facing a labeling tool with too many approval gates was to bundle tasks into bigger, slower, less iterative experiments, which is the exact opposite of what a foundation lab racing toward self-improvement needs.
This is the GitHub turnaround playbook — only literal.
“It had to be kind of perfect when it shipped. And so it was like, okay, break the stage fright. We’re gonna just throw a lot of pots and hopefully we get good at this eventually.”
— Friedman, on his GitHub-era cure for shipping paralysis
“Organizations entropically decay to the point where they’re situated at the atomic level to prevent progress. It’s not anyone’s fault. It’s just an emergent phenomenon of local incentives.”
— Friedman
“I don’t pay any attention to the org chart. … There’s that meme of the conspiracy guy with the push pins and the string — that’s what my org chart looks like.”
— Friedman
The image that lands hardest: an MSL leader treating Meta’s labeling pipeline the way he treated GitHub’s CI/CD gap in 2018 — walk in, talk to the doers, find the binding constraint, rip out the tool, ship the replacement. When MSL claims later this year that it’s running 5–10x more labeling experiments per week than it was in March, that won’t be a compute story. It’ll be a permission-slip story.
FinOps for tokens — the budget primitive of the next decade
The other genuinely new disclosure from Gross was a working theory of how to budget AI work inside a large company.
“At Meta, and I think many other companies, for the first time, individual ICs in everyone’s business have the ability to rack up a lot of charges using a bunch of different APIs. … The problem we’re working on that I think everyone will have to start working on is what is the right way to think about attributing budget to individual people. … A product I think we’re working on, and I think everyone else will build, is just using of course language models to understand the economic value of the generated tokens.”
— Daniel Gross
“We are all kind of portfolio managers in a hedge fund, and every IC you have is running a strategy and you have to decide how much budget you’re going to allocate to their strategy.”
— Daniel Gross
In English: every Meta engineer has a token budget. The output of their token spend gets graded (by another LLM) for economic value. A manager at Meta is no longer a headcount allocator. They are a portfolio manager allocating risk capital across strategies, where each IC is one strategy.
This isn’t a fully unique observation. The CFO/CIO X discourse converged on this framing in the months running up to Sessions:
Establish token budgets per role (like SaaS seats) … Track tokens per outcome, not just per user … Implement AI FinOps + guardrails.
— @dhinchcliffe Apr 30, 2026
This is the FinOps moment, compressed. Cloud bills outran finance teams in 2018. AI bills will outrun product teams this year.
— @StationDeltaHQ Apr 26, 2026
The shitpost version, with 316 likes — the engagement signal that this hit a nerve:
Thank you for the job offer. However, before we move forward I need to understand my monthly token budget.
— @TheRealAdamG Apr 30, 2026
What’s new is Gross saying Meta is shipping it as an internal product. The closest external analog is the cloud-FinOps category that emerged in 2018–2020 (companies like Apptio, Vantage, CloudHealth), except those were retrospective billing-attribution tools. The Gross primitive is prospective allocation: every IC opens a quarter with X tokens, every artifact they produce gets graded by an LLM judge, the manager rebalances toward strategies producing higher economic value per token.
Three load-bearing implications:
-
Headcount is no longer the right reporting metric. A team that spent 100M tokens and produced two trained labelers worth $1B in downstream model lift is more valuable than a team that spent 10M tokens and shipped a polished demo no one used. Gross is explicit that this is the analog to portfolio management.
-
There’s a two-LLM stack inside Meta now. One LLM does the work, a second LLM grades the work. The grading LLM has to be calibrated, tuned, and audited — a job that doesn’t exist on any org chart yet.
-
The headcount-down narrative may be wrong. Gross openly disagreed with the consensus that mag-7 companies should shrink: “the tech companies we know of today [aren’t] producing the right products at the perfect rate. … I strongly suspect the entire debt for startups is that these companies are very inefficient.” This is contrarian for an MSL leader given that Meta announced ~8,000 layoffs the same earnings cycle. Read together: the problem isn’t excess headcount — it’s bad org structure dressed up as efficiency.
The China/WTO frame for the singularity
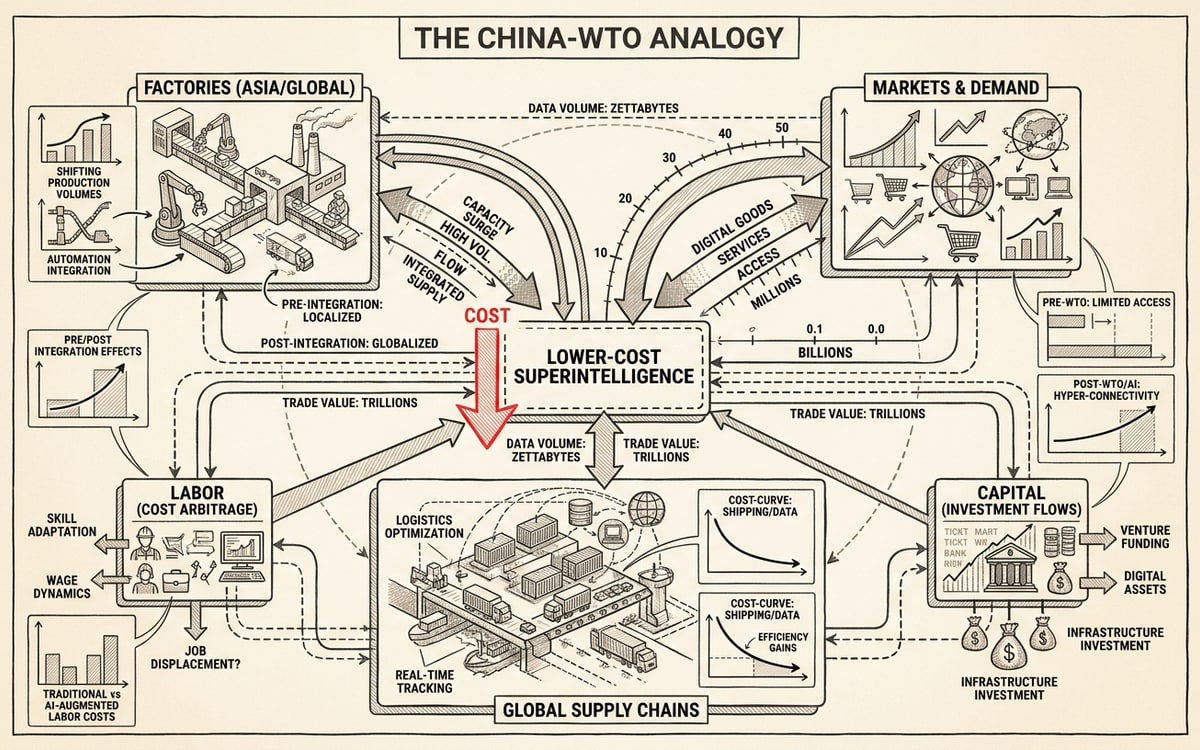
Gross’s macro framing (that “the last time we connected a lower-cost superintelligence to the global economy” was when China joined the WTO) is the post-able take from the talk. The China shock was deflationary on goods and inflationary on housing/healthcare/education simultaneously, and the AI version likely shows the same split sign.
“We don’t even know what the sign bit is going to be on any of this stuff.”
— Friedman, interjecting
That’s not modesty — that’s the actual unknown. AI is plausibly disinflationary on services that compress into tokens (legal review, code review, customer support, the finance G&A function the Collisons spent ten minutes asking about) and inflationary on the inputs to AI itself: power, GPUs, real estate near substations, hyper-skilled labelers, and coordination labor inside the labs themselves.
The corollary argument was made the same week:
AI modularizes execution, which sends scarcity to context and trusted operations. Transacting externally is now (apparently counterintuitively) more expensive.
— @hypersoren May 1, 2026
The modularization frame pairs with Gross’s macro: AI compresses execution costs, which drives the economic value of coordination, context, and trust, exactly the surfaces Stripe, Meta, and OpenAI all care about owning.
What MSL’s consumer surface will look like — Friedman’s vignettes
Friedman spent twenty minutes telling stories that read on first listen as personal-tinkering content and on second listen as a head-of-product walkthrough. The Vizia face scanner he bought on eBay, then reverse-engineered with Claude Code in 90 minutes when the encryption dongle was missing. The Raspberry Pis on every screen in his house running custom dashboards. OpenClaw with --dangerously-skip-permissions, hooked to his security cameras, his blood tests, his DNA, and his Tesla — the agent that determined he was dehydrated, watched him on camera, told him to walk to the kitchen, and then sent him a snapshot of him drinking a bottle of water with a “Good job”.
“I can see you on the camera. I want you to walk to the kitchen right now and drink a bottle of water and I’m going to watch to make sure you do it.” … And I felt like I did do a good job.
— Friedman, recounting his agent
“Most people when they run Claude Code or Codex, they run it with
--dangerously-skip-permissions. … People are really counting on the model’s agentic alignment right now. And the truth is, it’s not safe.”— Friedman
Two things to take seriously here.
First, this reads as Friedman previewing what Meta will ship as its consumer-AI product. Compare to Zuck’s July 2025 Personal Superintelligence note, repeated on the Q1 2026 earnings call as “on track to deliver personal superintelligence to billions of people.” Meta’s framing has converged on agents that live with you, see what you see, and act on your behalf. The eBay story isn’t tinkering — it’s the storyboard.
Second, the safety framing is genuinely radical. Friedman endorses the “start with everything-permitted, climb the nines on safety” approach over the OpenAI-default “start safe, slowly add capabilities.” He calls the alternative “so lame and boring and gimped.” That choice (about which side of the Pareto frontier you walk back from) is the consumer-AI alignment debate of 2026, and the head of product at Meta’s superintelligence lab just publicly took the high-capability side. The bet is that Meta can climb the nines fast enough that the agentic-alignment failure rate gets to whatever consumers tolerate before the press cycle catches up.
The LeCun shadow
The most striking absence in 90 minutes was Yann LeCun’s name. LeCun was Meta’s chief AI scientist for 12 years before leaving in November 2025 to launch a new lab focused on Advanced Machine Intelligence — explicitly a non-LLM bet. He’s been vocal in the press and on X that the industry is “LLM-pilled” and that scaling LLMs to AGI is wrong-headed.
Friedman’s stage thesis, that “the prime project at every AI lab right now is to remove humans from the loop … and get to self-improvement,” is the precise bet LeCun rejected on his way out. Gross’s framing of “global GDP would be just under 1%” of capex aimed at scaling exactly that bet is the price tag LeCun called too high for too narrow a paradigm.
Neither named him. The implication, played politely, is that MSL is no longer the place where that debate is open.
What this means for the rest of the AI economy
The composite from these 90 minutes: Meta’s AI division is now run by ex-investors with operator backgrounds, has internalized the GitHub-era tooling-and-tempo playbook, has reframed compute and tokens as portfolio-management problems, and has made an explicit bet on capability-first consumer agents. None of that was the framing in the August 2025 press cycle. The entire reorg was reported as a Wang-led talent saga. Gross and Friedman just rewrote it as a systems and metabolism story.
For Stripe, Gross’s closing advice was crisp:
“If a new continent was to be discovered — which are going to be these agents — what exactly would that be, and how can you build for it? … I don’t know that the Treasury will be giving them social security numbers. So my guess is they’re going to like stablecoins.”
— Gross, closing the talk
That line lines up with Part 1 of this series, where Stripe’s Tempo + Bridge stack and the Machine Payments Protocol made stablecoin settlement the default for agent commerce. It also tracks the Coasean-singularity debate on X about whether AI consolidates economic activity inside large agents or fragments it across billions of micro-transactions — a debate that maps directly onto whether Stripe’s TPV (1.6% of global GDP per the keynote) can keep growing alongside Meta’s 1%-of-global-GDP capex line.
What to watch for the next twelve months
Here is the position to take.
The MSL story for the next twelve months will not be a compute story or a model-architecture story. It will be a permission-slip story. Meta has already won the capex race — @vic_crane noted that Meta raised AI capex by $107B in a single guidance cycle, a fait accompli. The four hyperscalers will collectively spend ~$700B in 2026 (Om Malik).
What determines whether MSL ships a frontier model that matters is whether Friedman’s tooling-and-tempo intervention propagates beyond the labeling pipeline into RL environment construction, eval pipelines, post-training tuning, and inference-time orchestration. The failure mode is well-known: GitHub turnarounds work in 2,000-person companies. Meta has 75,000 employees. The activation-energy problem doesn’t shrink linearly.
If Friedman pulls it off, the second-derivative bet is that Gross’s portfolio-manager framing becomes the management primitive of the next decade — every AI-native company runs on token budgets allocated by managers acting like risk officers, with LLM-graded artifacts as the unit of account. The first vendor to ship a credible “Vantage for tokens” with native integrations into Anthropic Workbench, OpenAI Admin, and Bedrock owns a category.
If Friedman doesn’t pull it off, and the binding constraint is genuinely org size rather than legacy tools, then @taobanker’s question becomes the right one to ask Zuckerberg every quarter for three years. The honest answer at that point is that the investments aren’t ROIC-positive and that the LeCun frame, that scaling LLMs to AGI is the wrong project, was right, with the bill paid by the LP base of an entire industry.
The disclosure on stage at Stripe Sessions should be read as the inside operators saying, calmly, in public: we know which one it is. The bottleneck is permission slips, not GPUs. Watch what we ship.
Series: Stripe Sessions 2026, Part 2. Read Part 1: The complete developer’s guide to Stripe Sessions 2026 for the protocol stack and shippable surface area, and see Karpathy on Software 3.0 for the agentic-engineering frame these tooling overhauls live inside.